Meet Michael Thayer | A Strategy-First Approach To Mortgage Lending
Most Lenders Start With The Rate. I Start With The Strategy.
Most mortgage conversations begin with an interest rate, a loan program, or the maximum amount someone can qualify for. I begin with what you are trying to accomplish. Your mortgage affects your monthly budget, cash after closing, future flexibility, and long-term financial plans. Before choosing the loan, we build the strategy.
Why I Built A Strategy-First Mortgage Process
Why I Built A Strategy-First Mortgage Process
A Mortgage Approval Tells You What You Can Borrow. A Strategy Tells You What You Should Do.
Getting approved matters, but approval isn't the same as a financial plan. The highest purchase price or lowest advertised rate doesn't automatically mean the best mortgage.
I help clients compare the complete picture: monthly payment, cash required at closing, mortgage insurance, seller incentives, interest-rate options, future flexibility, and long-term cost. The goal is not simply to close the loan. The goal is to help you make a decision you understand before you commit.
What You Can Expect:
➡️ Education Before Decisions
- Understand the options and trade-offs before choosing a mortgage strategy.
➡️ Strategy Before Shopping
- Build the financing plan before the pressure of making an offer begins.
➡️ Clear Side-By-Side Comparisons
- Compare different loan structures, payments, and upfront costs.
➡️ Communication From Start To Finish
- Know where the loan stands, what has been completed, and what happens next.
➡️ Guidance Beyond Closing
- Continue receiving mortgage, housing-market, and long-term planning resources after the transaction is complete.

Your Roadmap To Homeownership
Most buyers see the mortgage process once and are then expected to remember every document, deadline, and milestone while also searching for a home, negotiating an offer, and preparing to move.
That is not a communication plan. It is a recipe for uncertainty.
Mortgage GPS provides a clear roadmap from the first strategy call through closing and beyond.
Mortgage GPS™ Shows You:
➡️ Where you are in the process
➡️ What happens next
➡️ Which documents are needed
➡️ Which milestones have been completed
➡️ What to expect before closing
➡️ How the journey continues after closing
Instead of wondering what comes next, you have a clear path forward.
➡️ Click the Mortgage GPS™ roadmap below to explore each step of the homebuying process.
Your Weekly Communication Hub
You Should Never Have To Chase Your Mortgage Team For An Update.
Getting a contract accepted is only the beginning. Once the loan is underway, silence creates stress for the buyer, seller, and real estate agents involved.
You should not have to send repeated messages just to find out whether the loan is on track.
Our Weekly Communication Hub gives the transaction’s key participants one organized place to follow the loan from contract through closing.
Your Weekly Communication Hub Includes:
➡️ Current loan status
➡️ Completed milestones
➡️ Outstanding action items
➡️ Upcoming deadlines
➡️ Weekly progress updates
➡️ Important contacts
➡️ Key contract dates
➡️ What our team is working on behind the scenes
Instead of chasing updates, you'll know what's happened, what still needs to happen, and what comes next.
➡️ Click the Weekly Communication Hub below to see how we keep clients and real estate partners informed.
Experience Matters. But How That Experience Is Used Matters More.
Michael Thayer is a Certified Mortgage Planning Specialist and Certified Mortgage Advisor with more than two decades of mortgage-lending experience. He is known for turning complicated financing decisions into clear, side-by-side comparisons that clients and real estate partners can understand and use.
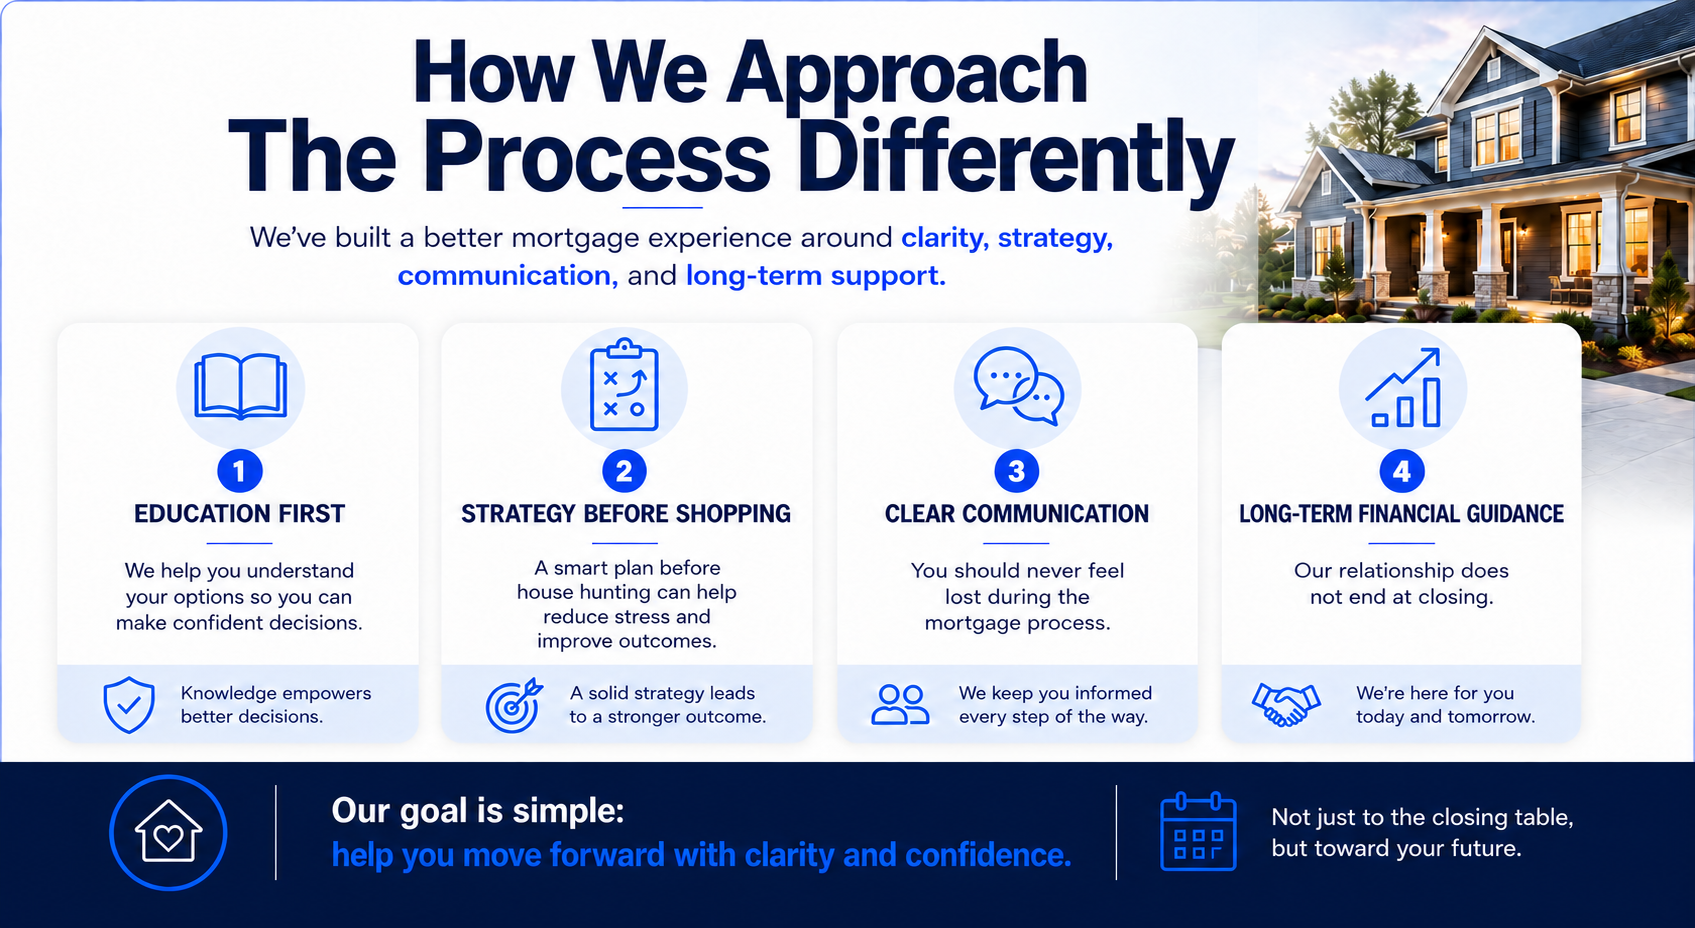
His approach is built around four commitments:
➡️ Education First
- Understand your options before deciding.
➡️ Strategy Before Shopping
- Create the mortgage plan before choosing the property or making the offer.
➡️ Clear Communication
- Know where the transaction stands and what happens next.
➡️ Long-Term Financial Guidance
- Consider how today’s mortgage fits into tomorrow’s goals.
The process is not built around closing one loan. It is built around helping you make a stronger decision.
Different Goals Require Different Mortgage Strategies.
A first-time buyer, move-up homeowner, investor, Realtor, and builder shouldn't get the same mortgage conversation. The right strategy depends on the person, the property, the transaction, and the goal.
➡️ Homebuyers
- Build a plan around the monthly payment, cash required at closing, available loan programs, and long-term goals.
➡️ Homeowners And Sellers
- Explore refinancing, home equity, seller-transition, and buy-before-you-sell strategies.
➡️ Real Estate Investors
- Compare cash flow, leverage, equity, financing costs, and opportunities to grow a real estate portfolio.
➡️ Realtors
- Use property-specific affordability tools, financing strategies, listing resources, and transaction communication to help more clients move forward.
➡️ Builders And On-Site Sales Teams
- Address affordability concerns and home-sale contingencies that prevent interested buyers from completing a purchase.
Why Clients Choose Michael Thayer
Clients should never feel like a loan number moving through a system. They should understand the strategy, know where the transaction stands, and feel confident that someone is paying attention to the details.
Our process combines:
➡️ Communication
➡️ Strategy
➡️ Education
➡️ Market insight
➡️ Payment planning
➡️ Confidence throughout the transaction

What Clients Are Saying
A successful mortgage experience should be measured by more than whether the transaction closed. Clients should feel informed, prepared, and supported throughout the process.
Michael has earned a 4.94-star rating across 175 client reviews, with clients frequently highlighting his communication, knowledge, responsiveness, and ability to make complicated transactions easier to understand.
➡️ Read More Client Reviews At The Top of The Page
More About Michael
Michael Thayer is a Certified Mortgage Planning Specialist and Certified Mortgage Advisor with more than two decades of mortgage-lending experience. His work includes home purchases, refinancing, cash-out refinancing, move-up buyers, real estate investors, seller-transition strategies, affordability planning, and Realtor and builder partnerships.
Based in Nashville, Tennessee, Michael helps clients and real estate professionals in Middle Tennessee and across the markets supported by his licensing and available mortgage programs.
His approach is straightforward: understand the goal, study the numbers, explain the tradeoffs, and build the strategy before asking the client to make the decision.
Outside of mortgage lending, Michael lives in Nashville with his wife, Tammie, their two children, and three Great Danes. He enjoys spending time with his family, traveling, watching college and professional football and hockey, and cheering for the Boston Red Sox.
Every Homebuyer's Journey Is Different
Your Next Step Should Match Your Goal.
You do not need to know which mortgage program you want before starting the conversation. You only need to know what you want the next move to accomplish.
Not Sure Where To Start?
Schedule a short mortgage strategy call. We will discuss your goals, timeline, preferred monthly payment, available funds, current property, and the questions you need answered before you move forward.
➡️ Schedule Your Mortgage Strategy Call
Ready To Begin?
Submit your mortgage application securely. Once we receive your information, our team will review it and contact you to discuss available options and next steps.
➡️ Submit Your Mortgage Application
Are You A Realtor Or Builder?
Schedule a partner strategy call to discuss listing affordability, buyer financing, seller-transition strategies, property-specific marketing, or home-sale contingencies.
➡️ Schedule A Realtor Or Builder Strategy Call
Best regards,
Michael Thayer, CMPS, CMA
NMLS #173264
Planet Home Lending, NMLS #17022
Where Would You Like to Go Next?
+ −Market Timing vs. Market Strategy: When Is the Right Time to Buy... And More Importantly, Why?
Calculators & Loan Programs Questions Answered: Mortgage Programs & Financing Calculator
Smart Financing Strategies to Lower Your Monthly Mortgage Payment: Smart Mortgage Strategies & Financing Hacks
Homebuying Roadmap: Your Mortgage GPS
Moving To Middle Tennessee: Moving To Middle Tennessee Resource Center
Search Open Houses: View All Middle Tennessee Open Houses
Main Resource Hub: Buyers, Sellers, Realtors, and Builders Resources and Strategies
Video Transcript
+ −00:00
When you're buying a house, getting approved for the maximum amount should not be your goal, people. Getting approved for a mortgage that still lets you live your life.
00:08
should be your goal. More importantly, develop a strategy before you even start shopping for houses. I'm Michael Thayer. I've spent more than 20 years turning complicated financing into clear, side-by-side choices, explaining words that you can actually understand. While most lenders are going to start with the rate, the loan program, and the maximum approval.
00:25
I'm going to start with what you're actually trying to accomplish because an approval just tells you what you can borrow. A strategy helps you decide what you should do and when.
00:36
I'm not here to quote your rate and hope that the best and everything else works out for you.
00:40
We compare how each option affects your monthly payment, your cash to close future flexibility before you're under pressure to make an offer and under a contract to perform. It's simple. We follow the numbers and connect the dots.
00:54
So that you understand what you're doing, why, and how it benefits you. And then once you're ready to move forward, you should never have to chase your mortgage team around for an update. Our mortgage GPS shows you exactly where you are in the process and what happens next. Our weekly communication hub keeps sellers, buyers, and agents informed from contract to closing, whether you're buying, refinancing, investing, selling, or helping a client.
01:18
Your mortgage should be built around your goals, not the other way around.
01:23
That's what Strategy First Mortgage Lending looks like. So take a look around, check out the pages, and look at the next step that matches what you're trying to accomplish. And then, when you're ready, let's build a strategy that works for you and make the right decision for you and your family.
Why So Many Buyers Feel Overwhelmed Today - Image Overview
+ −What this image communicates
This image explains why buying a home and choosing a mortgage can feel overwhelming even before a buyer makes an offer. It identifies four common causes of homebuyer stress: too many financing options, conflicting mortgage advice online, poor communication during the loan process, and unclear expectations or timelines. The image shows a concerned couple reviewing information at a table, with questions about money, communication, scheduling, and homeownership surrounding them. Its central message is that buyers need more than a mortgage approval. They need a modern, transparent mortgage experience built around education, strategy, communication, and a clear roadmap.
Why it belongs on this page
The Meet Michael Thayer page explains a strategy-first approach to mortgage lending. Before visitors can understand the value of that approach, they need to recognize the problems it is designed to solve. Many buyers receive loan-program information without understanding how the options compare. Others search online and find conflicting answers that create more uncertainty. This image connects those frustrations to Michael’s approach: personalized mortgage planning, side-by-side loan comparisons, clear communication, and guidance throughout the homebuying process.
How a reader can use it
Identify which part of the mortgage process is creating the most uncertainty. If the number of mortgage programs feels overwhelming, request a side-by-side comparison based on your goals, payment range, down payment, and available funds. If online mortgage information conflicts, ask how the advice applies to your income, credit, property, location, and loan scenario. If communication or timing is the concern, review the Mortgage GPS™ roadmap and Weekly Communication Hub to understand how documents, loan milestones, deadlines, and closing updates are organized throughout the transaction.
What still must be verified
Every mortgage strategy depends on the buyer’s complete financial profile and the property being purchased. Verify income, employment, assets, credit, debts, down payment, available funds, occupancy, property type, loan amount, interest rate, mortgage insurance, taxes, homeowners insurance, association dues, closing costs, and loan-program eligibility. Online information and general mortgage education cannot replace a personalized loan review. Current lender guidelines and underwriting establish which programs, terms, and financing options are available.
How We Approach The Process Differently - Image Overview
+ −What this image communicates
This image presents Michael Thayer’s mortgage process as four connected commitments: Education First, Strategy Before Shopping, Clear Communication, and Long-Term Financial Guidance. Education First helps clients understand their mortgage options before deciding. Strategy Before Shopping establishes the financing plan before the pressure of choosing a property or submitting an offer. Clear Communication keeps the client informed throughout the mortgage process. Long-Term Financial Guidance considers how the mortgage fits into the client’s plans beyond closing. The image’s central promise is to help clients move forward with clarity and confidence, not simply reach the closing table.
Why it belongs on this page
The Meet Michael Thayer page should explain more than Michael’s professional background. It should show visitors what working with him actually looks like. This image turns the strategy-first philosophy into a simple four-part process that buyers, homeowners, investors, Realtors, and builders can understand. It supports the page’s message that a strong mortgage experience begins with education and planning, continues through consistent communication, and remains connected to the client’s longer-term financial goals.
How a reader can use it
Use the four commitments as a checklist when preparing for a mortgage conversation. Begin by identifying the decision you are trying to make and the questions you need answered. Build the financing strategy before setting a home-price target, making an offer, refinancing, or using home equity. Request clear comparisons of the monthly payment, cash required at closing, loan structure, mortgage insurance, interest-rate options, and long-term costs. During an active transaction, use the Mortgage GPS roadmap and Weekly Communication Hub to follow milestones, documents, deadlines, and next steps.
What still must be verified
A strategy-first review does not guarantee mortgage approval, a specific interest rate, a particular monthly payment, or a successful closing. Verify the client’s income, employment, credit, assets, debts, available funds, property details, occupancy, loan amount, and program eligibility. Interest rates, annual percentage rates, discount points, closing costs, mortgage insurance, lender requirements, and underwriting guidelines can change. Long-term mortgage planning should also account for the client’s personal budget, expected ownership period, future goals, and guidance from appropriate tax, legal, or financial professionals.
Why Clients Choose Michael Thayer - Image Overview
+ −What this image communicates
This image explains the combination of service, mortgage strategy, and education that defines the client experience with Michael Thayer. The left side highlights four reasons clients choose the team: Communication, Strategy, Education, and Confidence. Clients receive clear updates, a mortgage plan built around their goals, straightforward explanations of the mortgage process, and guidance intended to reduce uncertainty. The right side shows the educational resources supporting that experience: Understanding The Bigger Picture, Financing Strategy, Market Education, and Payment Planning. Together, the two sides show that the process combines personal guidance with practical mortgage tools and housing-market education.
Why it belongs on this page
Visitors to the Meet Michael Thayer page need to understand both who Michael is and what makes his mortgage process different. This image connects the personal service promise with the tools used to deliver it. Communication keeps clients informed. Strategy organizes the available financing options around the client’s goals. Education helps clients understand the decision instead of simply accepting a recommendation. Market insight and payment planning place the mortgage inside the larger housing and financial picture. The image reinforces that clients receive more than loan processing. They receive a coordinated mortgage-planning experience.
How a reader can use it
Decide which part of the mortgage decision requires the most clarity. Buyers can use payment planning and financing comparisons to establish a comfortable budget before shopping. Current homeowners can evaluate refinancing, home equity, or seller-transition strategies. Real estate investors can compare leverage, cash requirements, payments, and potential cash flow. Realtors and builders can use property-specific affordability tools, listing resources, market education, and structured transaction communication to support their clients. Visitors can then schedule the strategy call that matches their goal or begin a secure mortgage application.
What still must be verified
The services and resources shown in the image must be applied to each client’s actual circumstances. Verify financial information, mortgage objectives, property details, loan-program requirements, interest rates, closing costs, seller or builder contributions, market information, and program availability. Market education reflects available information and conditions at the time it is prepared and should not be treated as a guarantee of future rates, property values, market activity, or financial results. Mortgage approval and final loan terms remain subject to application, documentation, credit review, property review, underwriting, and all applicable program requirements.