What If Your Seller Could Move First — And You Keep the Listing?
Your seller doesn’t have to wait for their current house to sell before you give them a way to move forward.
We help solve the timing problem without taking the listing away from you, then help create more visibility, affordability, and buyer opportunity around YOUR listing.
Move The Seller First. Then Help Get The Listing Sold.
You Keep The Listing. Move Your Seller First. Create More Buyer Momentum.
You Keep The Listing. Move Your Seller First. Create More Buyer Momentum.
Part 1: Move the Seller First
Stop waiting for a contract on your seller’s current house before giving them a way to move forward on the next one.
If they need their equity for their down payment, can’t qualify carrying both mortgage payments, or simply don’t want the risk of two house payments, we can help them access their equity and buy the next house FIRST.
And YOU KEEP THE LISTING.
Now your seller can move forward without trying to perfectly time two transactions, while you get a decluttered, properly staged home that’s easier to show, easier to market, and positioned to sell at its full potential.
Click the image below to see the 3 ways we can help your seller buy first, reduce the stress, and keep YOU in control of the listing.
Part 2: The MLS Shows The House. We Show The Opportunity.
We’ve solved the timing problem. Now let’s create more buyer interest.
The MLS shows buyers the house.
We show them the financial opportunity behind the house.
We’re not just showing buyers a payment. We engineer an affordability strategy around YOUR listing and show, side by side, why seller concession dollars may work harder here than on another house.
Click the image below to see how we make YOUR listing stand out financially.
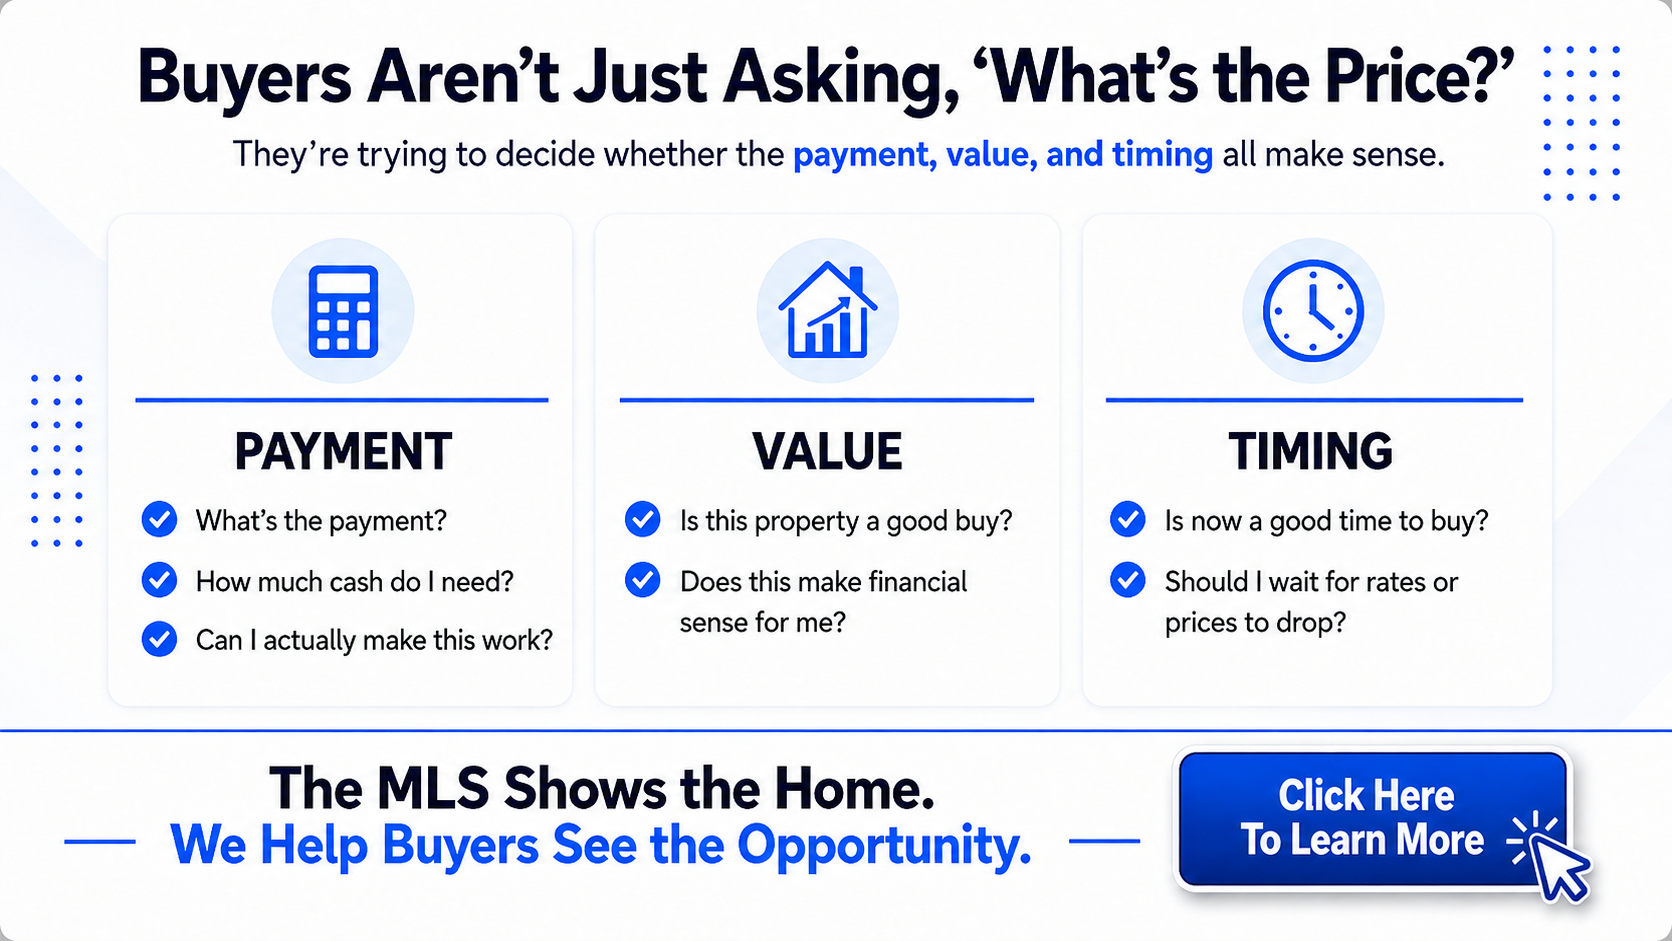
Buyers Evaluate Payment, Value, and Timing
Buyers Evaluate Payment, Value, and Timing
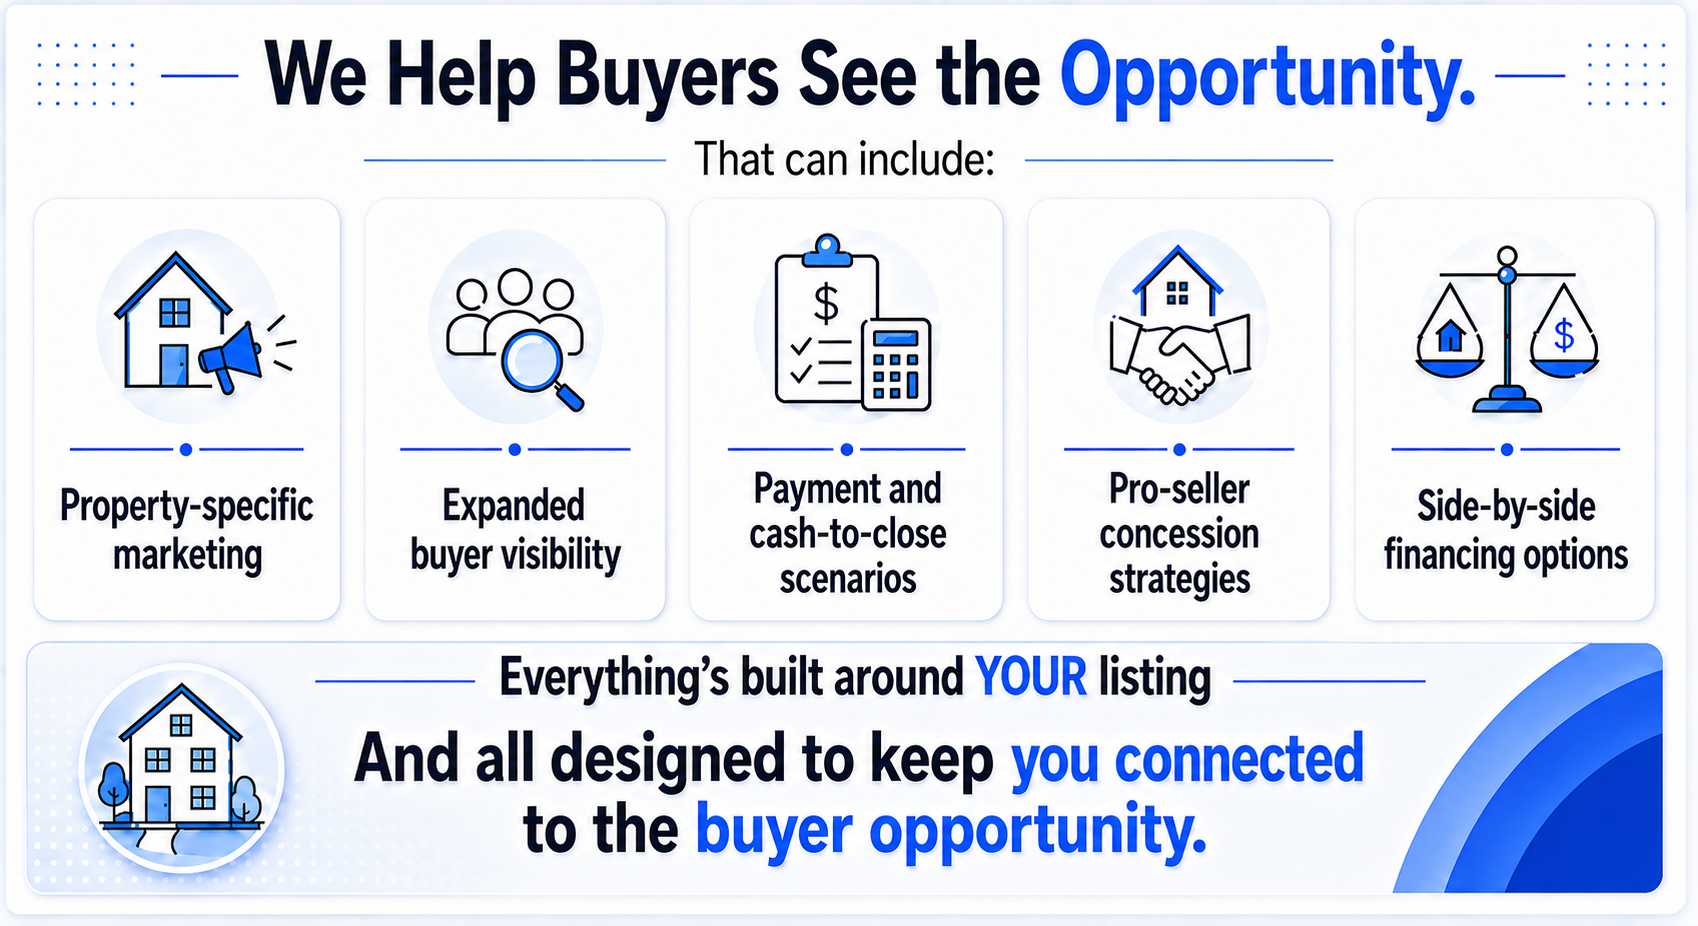
Property-Specific Buyer Opportunity and Financing Strategies
Property-Specific Buyer Opportunity and Financing Strategies
You Keep the Listing. You Keep the Relationship.
You handle the seller, the listing, the marketing, the negotiations, and the transaction.
We bring financing flexibility for your seller, affordability strategies for buyers, and property-specific marketing designed to increase visibility and buyer interest.
Want to See How This Could Work for Your Listing?
Let’s take a quick look at your property and determine whether the opportunity is to create more seller flexibility, more buyer visibility, or both.
➡️ Call or Text Michael @ 615-585-5900
Prefer to put a time on the calendar?
➡️ Schedule a 10-Minute Listing Strategy Review
Or, if you want to see the complete strategy first:
➡️ See The Full Seller Transition Plan
No presentation. No obligation. Just a quick look at the listing and whether there is another strategy worth putting on the table.
Best regards,
Michael Thayer, CMPS, CMA
Planet Home Lending
NMLS #173264 | Company NMLS #17022
Additional Information & Reference Guides
+ −Video Transcript
+ −00:00
Showings are slower, and your seller might start thinking they're stuck. And the longer that they stay stuck, the more your listing's at risk.
00:07
They need equity from their current house to buy their next one. And maybe they can't qualify carrying two mortgage payments, and they probably don't want to either. Or, they're possibly afraid to buy their next house first, because what happens if their current house doesn't sell?
00:20
And the last thing you want them doing is calling one of those "we'll buy your house for cash" companies and getting them unstuck. Because now you're gonna lose the listing. That's where we come in. We help your seller move first, access their equity, and buy their next house first. And you keep the listing.
00:38
We actually need you in the transaction. We're not trying to buy your seller's house. We'll buy it if we need to.
00:45
But we're not cutting you out of the deal. We're trying to help you sell it while we finance their next one. Now you have a vacant, decluttered home that you can stage and market properly. Then, we can help create property-specific affordability and buyer opportunities around your listing.
01:01
Move the seller. Keep the listing. Create more opportunity. Click below to see how these two strategies work together, and then let's connect to explore this on one of your listings and provide your seller with the solutions they're looking for to help them move forward. We'll talk to you soon.
Buyers Evaluate Payment, Value, and Timing Image Overview
+ −What buyers are evaluating
The “Buyers Evaluate Payment, Value, and Timing” graphic is divided into three buyer questions. Payment asks, “What is the payment, how much cash do I need, and can I make this work?” Value asks whether the property is a sound purchase and whether the financial structure makes sense. Timing asks whether buying now or waiting better serves the buyer. The three-column design matters because a buyer can like the house and still hesitate for three very different reasons; a price reduction does not automatically answer all three.
Why this image belongs on the listing strategy page
On “What If Your Seller Could Move First — And You Keep the Listing?,” the seller-transition problem has already been addressed. This image begins the second job: making the listing's financial opportunity easier for buyers to understand. It helps the agent diagnose whether a buyer objection is about monthly affordability, the value of the home and offer terms, or uncertainty about market timing. That diagnosis leads to a better follow-up than assuming every quiet buyer rejected the price or the property.
How an agent and lender can use it
For payment, build a verified loan scenario showing principal and interest, taxes, insurance, association dues, cash-to-close, points or credits, and any seller concession. For value, connect the listing's features, condition, comparable evidence, negotiated terms, and appraisal questions without promising an outcome. For timing, compare the buyer's current options with the uncertainty of future rates, prices, inventory, and competition. The benefit is a property-specific conversation that helps the buyer see which question needs an answer while the agent keeps control of the listing and client relationship.
What the three columns do not prove
The graphic is an educational decision frame, not a rate quote, appraisal, inspection, listing guarantee, or prediction. It cannot establish that the buyer qualifies, that the property is worth the asking price, or that buying now will outperform waiting. Every scenario must use current borrower, property, program, and market evidence, and every marketing statement must match the terms the seller has approved. If the price, concession, property facts, loan structure, or buyer profile changes, the comparison must be rebuilt.
Property-Specific Buyer Opportunity and Financing Strategies Image Overview
+ −What the five strategy cards show
The “Property-Specific Buyer Opportunity and Financing Strategies” graphic names five connected actions: property-specific marketing, expanded buyer visibility, payment and cash-to-close scenarios, pro-seller concession strategies, and side-by-side financing options. The cards are centered on the agent's listing rather than on a generic mortgage campaign. Their arrangement shows that exposure and financing are meant to support one another: the property story attracts attention, while accurate scenarios help an interested buyer understand how the opportunity could work.
Why the image is different from a standard MLS presentation
The MLS can show photographs, features, price, and basic property information. This graphic explains the additional financial questions Michael proposes to answer around that same listing. On “What If Your Seller Could Move First — And You Keep the Listing?,” the agent still handles the seller, marketing, negotiations, and transaction. The mortgage role is to provide verified buyer scenarios and compliant property-specific materials that may reveal options the listing alone does not communicate. The benefit is added buyer understanding without taking the listing relationship away from the agent.
How the five actions work together
Begin with accurate property facts and the seller's approved strategy. Build payment and cash-to-close scenarios for realistic buyer profiles, then compare financing structures or concession uses with the same price and closing assumptions. Use those verified figures in property-specific marketing and direct interested buyers to the exact explanation rather than to a generic rate claim. Track whether the material creates qualified questions, showing interest, or financing conversations. Each action should have a named owner, a current evidence source, and an expiration or refresh point.
What must remain conditional
The graphic does not promise more traffic, an offer, buyer approval, appraisal, seller acceptance, closing, or a better net result. Payment examples require disclosures and loan-specific assumptions; concessions remain subject to seller approval, contract terms, appraisal, program limits, and buyer eligibility. Property claims require current listing and disclosure evidence. The strategy is complete only when the material has been reviewed for the actual listing and every link or scenario works as presented on the live page.