Help Sellers Buy Before They Sell and Keep the Listing
No-Payment, No Upfront Cost Bridge Loan for Realtors
No-Payment, No Upfront Cost Bridge Loan for Realtors
A Tool Most Realtors Don’t Have Today
Your seller wants to buy their next home before their current home sells.
Traditionally, that leaves you with two bad options:
- Wait for the current house to sell and risk losing the home they really want.
- Or send them to one of those “Sell Your House for Cash” companies that can solve the seller’s problem while potentially taking the listing away from you.
Our Bridge Loan gives you another option.
Help your seller access their equity, buy their next home first, and you keep the listing.
Bridge Loan Uses: Turn Current-Home Equity Into Next-Home Buying Power
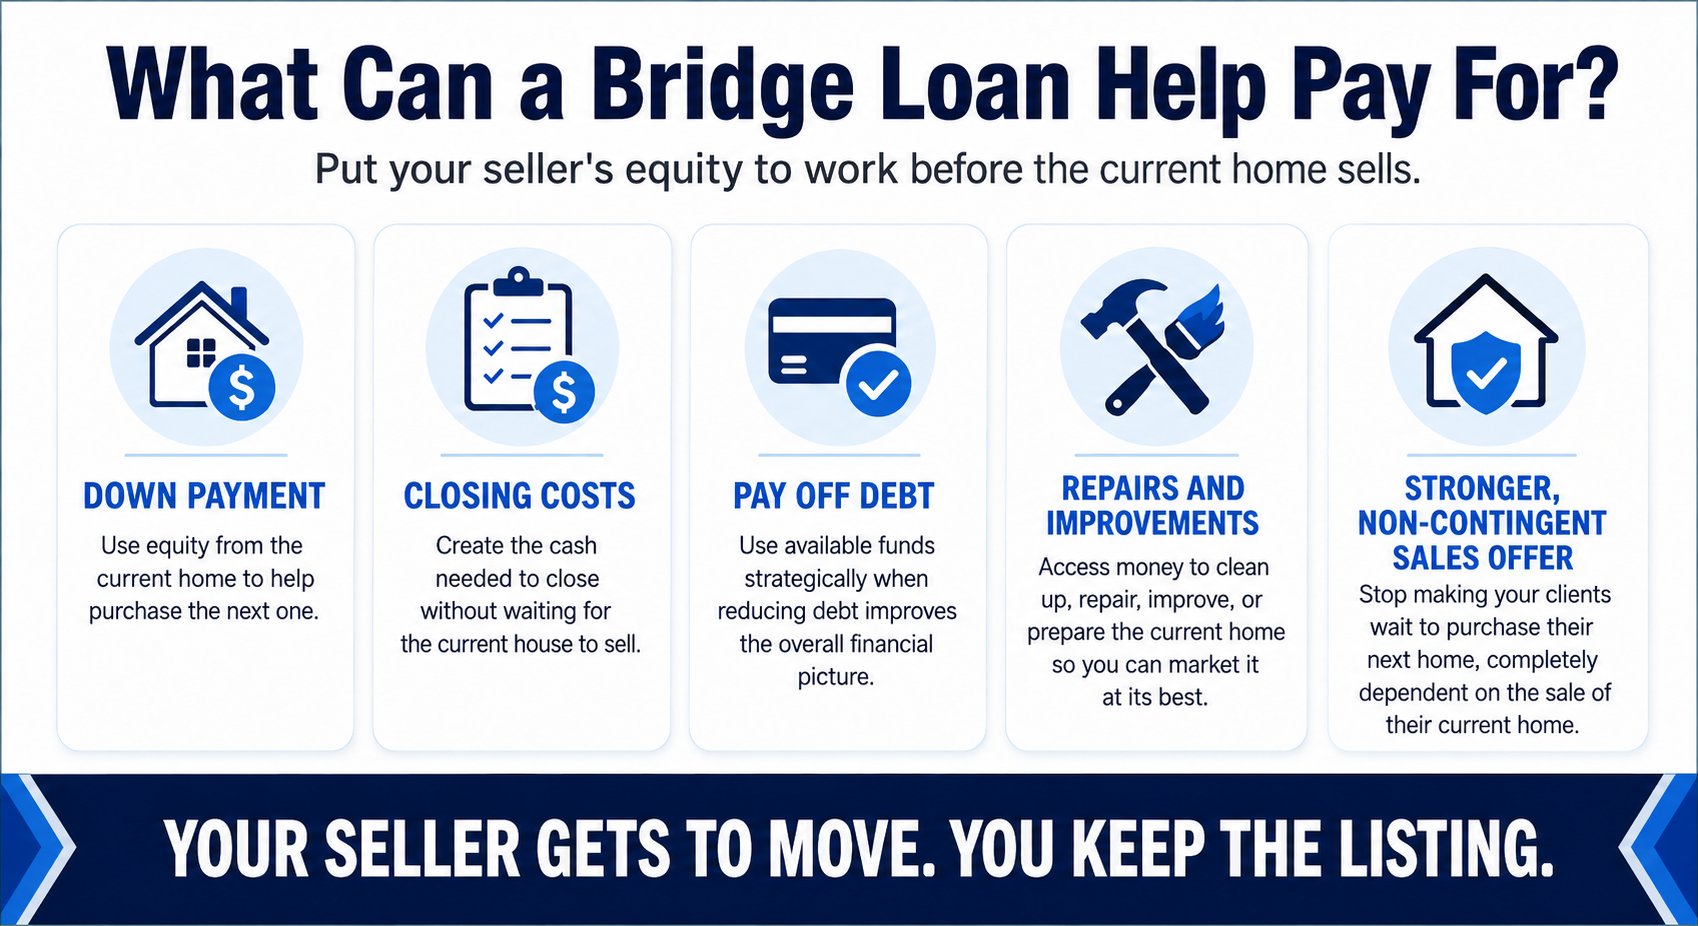
Bridge Loan Uses: Turn Current-Home Equity Into Next-Home Buying Power
Two Ways to Structure the Bridge Loan
Pay off their current mortgage or keep it in place. We structure the Bridge Loan around what creates the most flexibility for your seller.
Compare First-Lien and Second-Lien Bridge Loan Payment Structures
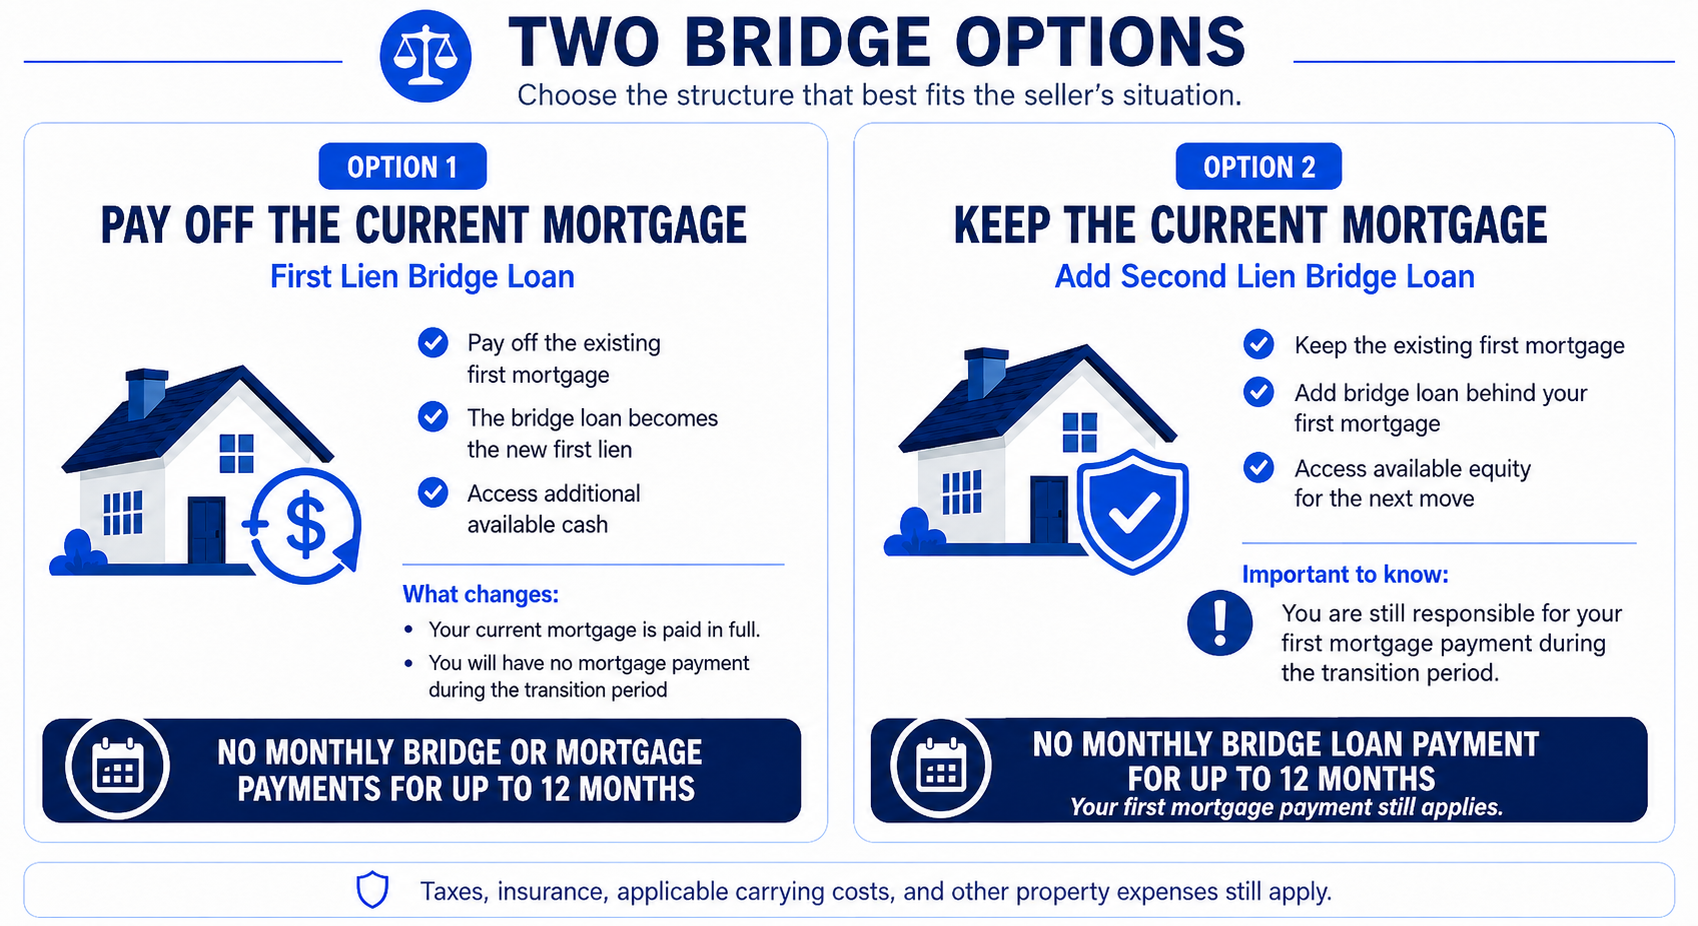
Compare First-Lien and Second-Lien Bridge Loan Payment Structures
Bridge Loan Costs Versus Cash-Home-Buyer Fees and Discounts
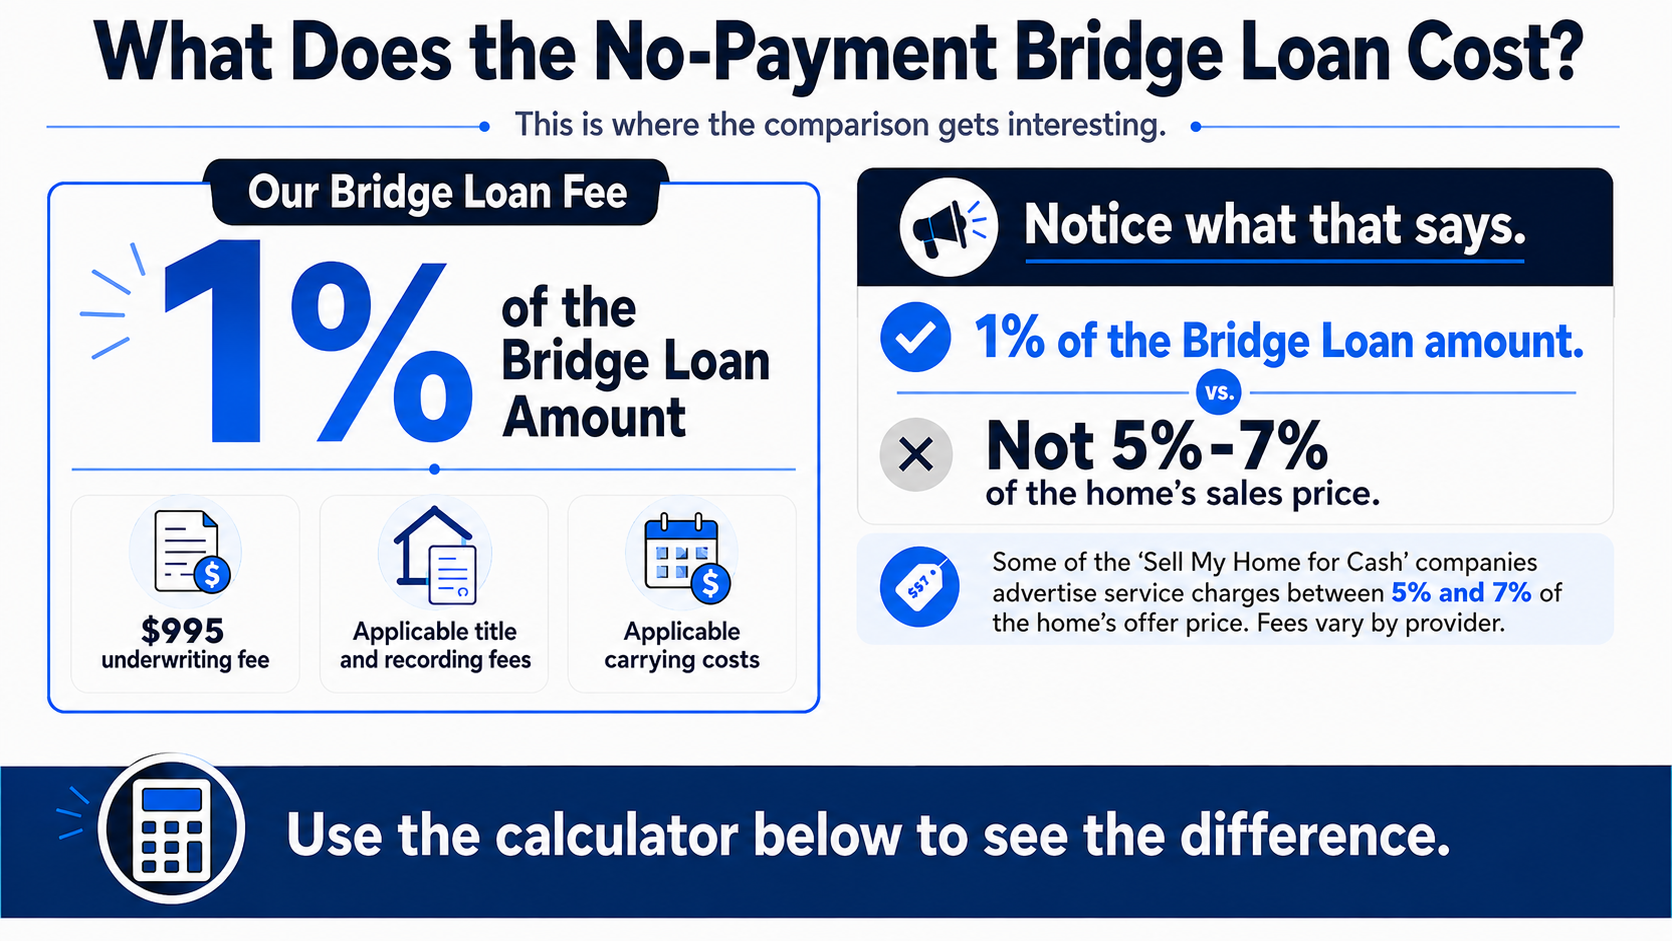
Bridge Loan Costs Versus Cash-Home-Buyer Fees and Discounts
Getting Your Seller Into the Next House Is Only Half the Win
Once they move out, think about what happens to the property you’re still selling.
Move First, Then Prepare the Current Home for a Stronger Market Sale
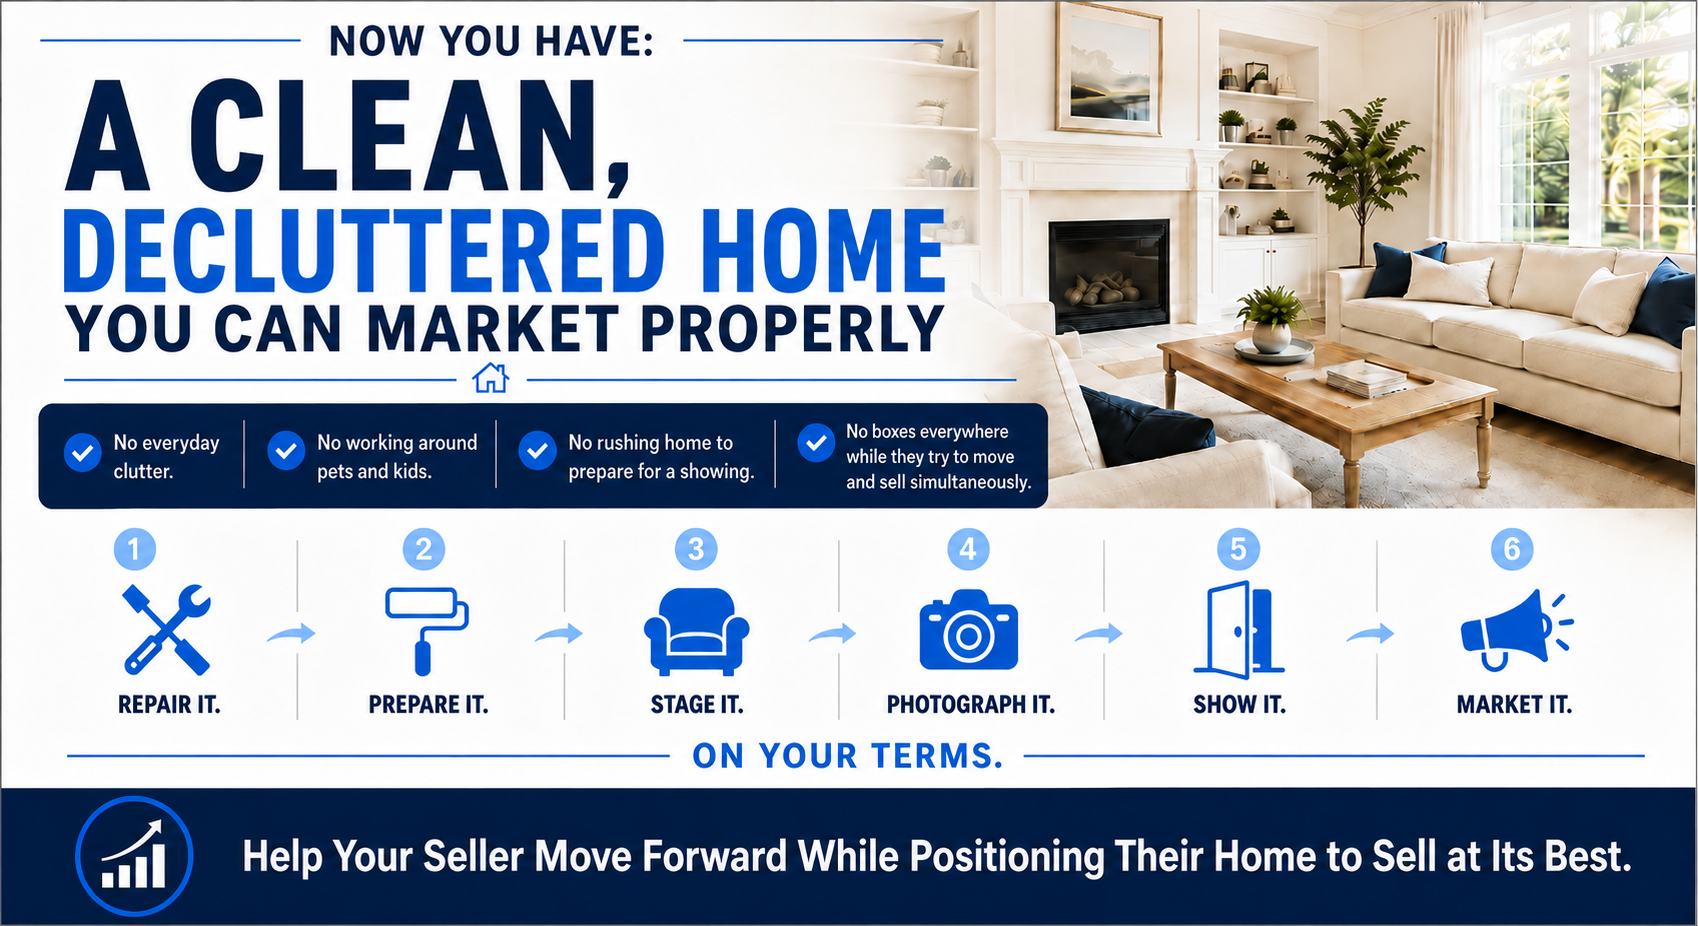
Move First, Then Prepare the Current Home for a Stronger Market Sale
Six Benefits of Bridge Financing Before the Current Home Sells
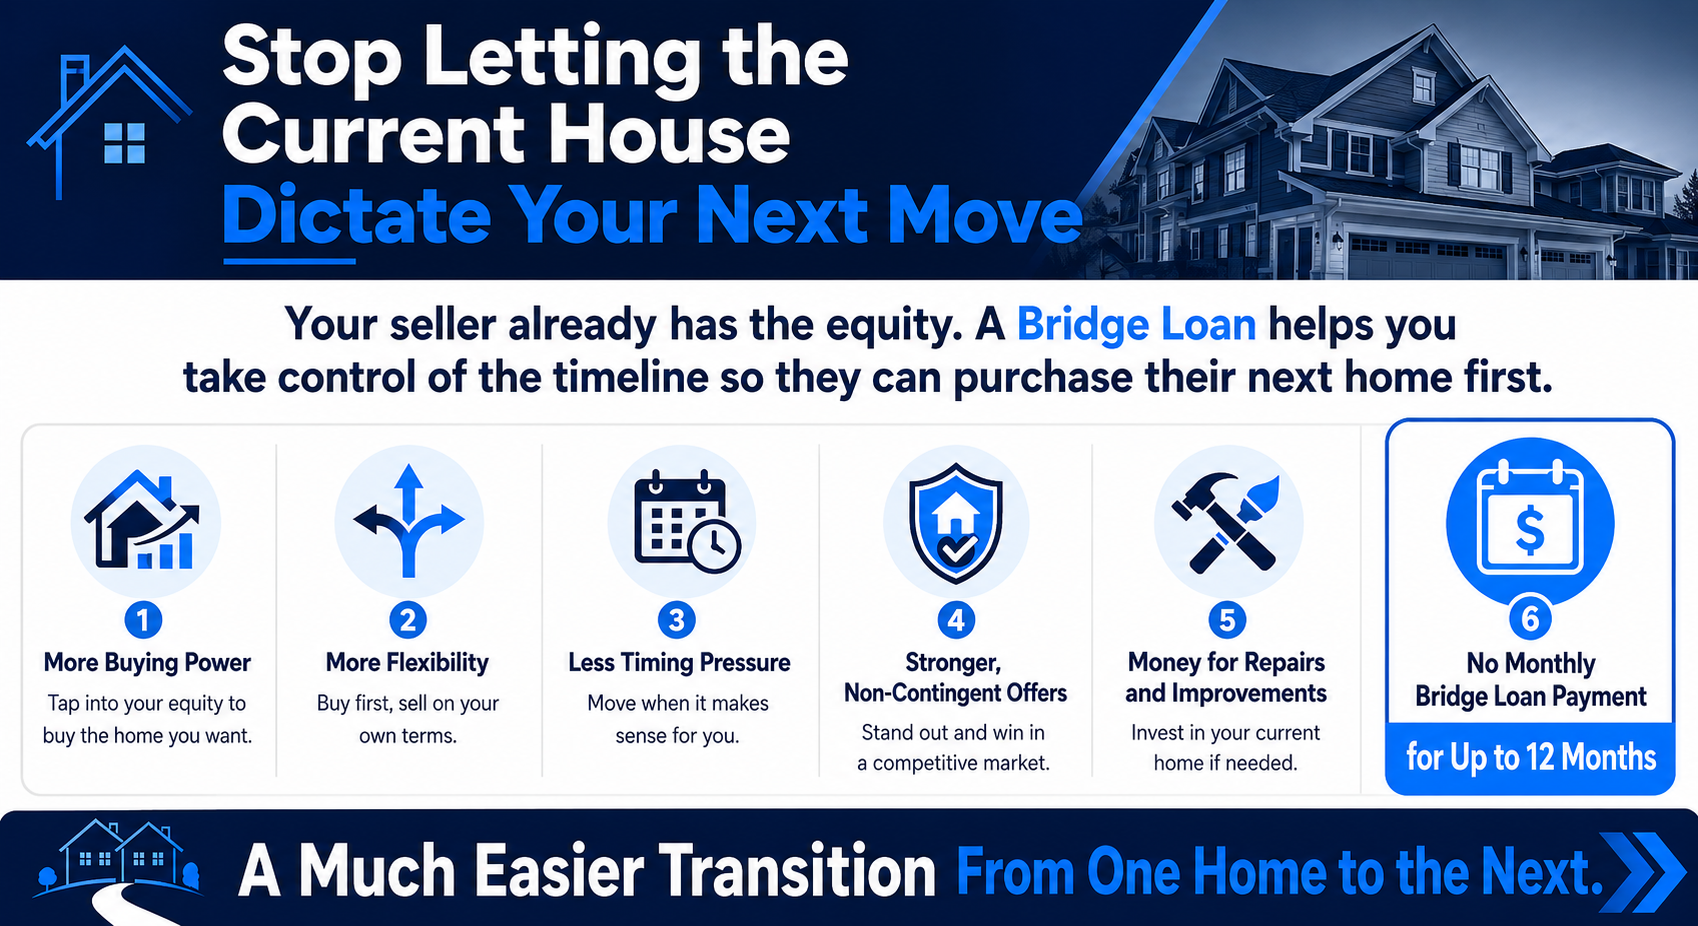
Six Benefits of Bridge Financing Before the Current Home Sells
Send Me the Property Address. Let’s Run the Numbers.
Let’s plug in the actual home value, current mortgage, available equity, cash needed for the next purchase, repairs, debt payoff, and estimated Bridge costs.
We’ll see whether the numbers create a better path forward before your seller makes a decision.
➡️ Call or Text Michael @ 615-585-5900
Prefer to put a time on the calendar?
➡️ Schedule a 10-Minute Listing Strategy Review
Already ran the calculator?
➡️ Send me the numbers, and I’ll review the scenario with you.
No presentation. No obligation. Just the numbers and whether the strategy makes sense for your seller.
Explore Other Ways To Move Before You Sell
Every situation is different. Explore these related strategies designed to create more flexibility, remove common roadblocks, and make the next move easier.
Explore the No-Payment Bridge Loan
- Access equity from the current home before it sells, create funds for the next purchase, and gain more flexibility over the timing of the move.
See How The Purchase EDGE Guarantee Works
- Resolve a qualification roadblock caused by the mortgage on the current home that is preventing the next purchase from proceeding.
Explore Purchase EDGE & The Guaranteed Backup Offer
- Keep the current home on the market while having a guaranteed backup buyer available if greater certainty is needed.
Best regards,
Michael Thayer, CMPS, CMA
Planet Home Lending
NMLS #173264 | Company NMLS #17022
Explore Buyer & Seller Resources & Next Steps
+ −Market Timing vs. Market Strategy: When Is the Right Time to Buy... And More Importantly, Why?
Calculators & Loan Programs Questions Answered: Mortgage Programs & Financing Calculator
Smart Financing Strategies to Lower Your Monthly Mortgage Payment: Smart Mortgage Strategies & Financing Hacks
Homebuying Roadmap: Your Mortgage GPS
Moving To Middle Tennessee: Moving To Middle Tennessee Resource Center
Search Open Houses: View All Middle Tennessee Open Houses
Main Resource Hub: Buyers, Sellers, Realtors, and Builders Resources and Strategies
Additional Information & Reference Guides
+ −Video Transcript
+ −00:00
Don't let one listing kill two transactions. Your seller more than likely has plenty of equity in their current home. The problem? It's trapped until they can sell their current home. And if you can't sell their current home.
00:13
That brings their plans to move to a new home to a screeching halt, because they can't access their equity for the down payment, they don't want to have two monthly mortgage payments, and they're afraid to make an offer before their current home sells, risking being homeless.
00:27
So what happens? They wait. Now they risk losing the next house that they want to buy. Or even worse, they start looking at those buy-your-house-fast-for-cash companies that would completely cut you out of the listing.
00:39
That's exactly what this bridge loan is designed to prevent. Use the calculator below to see how we can unlock their equity before they sell, with no monthly payments, no upfront costs, so that they can buy their next home first, and make stronger, non-contingent sales offers. And here's the part that matters most to you. You keep the listing!
00:59
You sell their current home, we finance the next one. We help protect the listing, we help create the next purchase transaction, and provide sellers who are stuck with a path to move forward.
01:11
You probably have a listing right now that you need help with. Send me the address. Let's create a path forward and offer the solutions that your sellers are looking for. Talk to you soon.
Bridge Loan Uses: Turn Current-Home Equity Into Next-Home Buying Power Image Overview
+ −What this image communicates
A reader encountering “Bridge Loan Uses: Turn Current-Home Equity Into Next-Home Buying Power” should immediately recognize the buy-before-selling and seller-transition strategy question inside “Help Sellers Buy Before They Sell and Keep the Listing.” The visual's role is primary visual message, so it must make one topic recognizable at a glance and give the reader a clear entry point into the deeper explanation on the page rather than merely repeat the headline. The visual centers “Bridge Loan Uses: Turn Current-Home Equity Into Next-Home Buying Power” on a specific housing or listing decision. It connects the visible promise to the property, the people involved, and the transaction sequence instead of leaving the message as abstract marketing. A useful reading separates what can be illustrated now from what still depends on the home's condition, the negotiated terms, verified financing, and current market response.
Why it belongs on this page
This Realtor-facing bridge resource explains how current-home equity can support the seller's next purchase while the agent keeps the listing. The primary visual message role of “Bridge Loan Uses: Turn Current-Home Equity Into Next-Home Buying Power” is the reason this image belongs at this point in “Help Sellers Buy Before They Sell and Keep the Listing.”
How a reader can use it
Use “Bridge Loan Uses: Turn Current-Home Equity Into Next-Home Buying Power” for its stated primary visual message job on “Help Sellers Buy Before They Sell and Keep the Listing.” Identify the claim, chart, comparison, process, property feature, or strategy shown and connect it to the exact decision the page addresses. The working notes for this panel should record the literal claim or comparison shown, the page fact it supports, the source behind that fact, and the decision the reader should make next. That record lets the reader identify whether the homeowner can move first while protecting the open-market listing and avoiding an unsupported promise about qualification or sale proceeds without asking this image to answer a different stage of the decision.
What still must be verified
The image does not approve financing, guarantee a sale, establish market value, remove contractual duties, or prove that one transition structure is best for every seller. “Bridge Loan Uses: Turn Current-Home Equity Into Next-Home Buying Power” should therefore be treated as a primary visual message, not as transaction evidence by itself. Current documents, responsible sources, and the professionals accountable for the relevant decision must control when they differ from the illustration. On “Help Sellers Buy Before They Sell and Keep the Listing,” that safeguard applies specifically to the primary visual message role assigned to “Bridge Loan Uses: Turn Current-Home Equity Into Next-Home Buying Power.”
Compare First-Lien and Second-Lien Bridge Loan Payment Structures Image Overview
+ −What this image communicates
“Compare First-Lien and Second-Lien Bridge Loan Payment Structures” establishes the visual entry point for this part of “Help Sellers Buy Before They Sell and Keep the Listing.” Its primary visual message framing helps the reader understand how to make one topic recognizable at a glance and give the reader a clear entry point into the deeper explanation on the page. The decision underneath the graphic is how equity, the current mortgage, next-home qualification, sale timing, liquidity, carrying costs, and backup plans interact. The visual centers “Compare First-Lien and Second-Lien Bridge Loan Payment Structures” on a specific housing or listing decision. It connects the visible promise to the property, the people involved, and the transaction sequence instead of leaving the message as abstract marketing. A useful reading separates what can be illustrated now from what still depends on the home's condition, the negotiated terms, verified financing, and current market response.
Why it belongs on this page
Its five images compare uses, lien and payment structures, costs versus cash-buyer discounts, move-first preparation, and six strategic benefits. The primary visual message role of “Compare First-Lien and Second-Lien Bridge Loan Payment Structures” is the reason this image belongs at this point in “Help Sellers Buy Before They Sell and Keep the Listing.”
The exact story carried by this graphic
The first-lien versus second-lien panel should show where a bridge loan sits in relation to the existing mortgage. A first-lien structure may replace or refinance the current debt; a second-lien structure leaves the first mortgage in place and adds another secured obligation. Payment treatment, available equity, lien priority, interest, fees, term, repayment, qualification, and payoff at sale can differ materially. The graphic helps the seller compare structure and total exposure rather than assuming “no payment” means no cost or no debt.
How a reader can use it
Use “Compare First-Lien and Second-Lien Bridge Loan Payment Structures” for its stated primary visual message job on “Help Sellers Buy Before They Sell and Keep the Listing.” Identify the claim, chart, comparison, process, property feature, or strategy shown and connect it to the exact decision the page addresses. The working notes for this panel should record the literal claim or comparison shown, the page fact it supports, the source behind that fact, and the decision the reader should make next. That record lets the reader identify whether the homeowner can move first while protecting the open-market listing and avoiding an unsupported promise about qualification or sale proceeds without asking this image to answer a different stage of the decision.
What still must be verified
The graphic has a defined limit: The image does not approve financing, guarantee a sale, establish market value, remove contractual duties, or prove that one transition structure is best for every seller. Use “Compare First-Lien and Second-Lien Bridge Loan Payment Structures” to understand and organize the issue, then rely on current source material for any number, eligibility rule, property fact, deadline, or professional conclusion. On “Help Sellers Buy Before They Sell and Keep the Listing,” that safeguard applies specifically to the primary visual message role assigned to “Compare First-Lien and Second-Lien Bridge Loan Payment Structures.”
Bridge Loan Costs Versus Cash-Home-Buyer Fees and Discounts Image Overview
+ −What this image communicates
On “Help Sellers Buy Before They Sell and Keep the Listing,” the “Bridge Loan Costs Versus Cash-Home-Buyer Fees and Discounts” visual isolates one decision from a larger housing conversation. As a primary visual message, it is meant to make one topic recognizable at a glance and give the reader a clear entry point into the deeper explanation on the page. The subject belongs to buy-before-selling and seller-transition strategy, where the useful question is how equity, the current mortgage, next-home qualification, sale timing, liquidity, carrying costs, and backup plans interact. The visual uses a side-by-side comparison to separate “Bridge Loan Costs Versus Cash-Home-Buyer Fees and Discounts” into alternatives that should not be treated as interchangeable. Its layout asks the reader to compare structure, cost, timing, eligibility, and consequence—not select a winner from one headline number. The comparison is therefore a decision aid, with each column pointing to a different fact that must be confirmed.
Why it belongs on this page
The page should help agent and seller coordinate the sequence without treating deferred payment as free money or assuming the open-market sale will meet a particular date or price. The primary visual message role of “Bridge Loan Costs Versus Cash-Home-Buyer Fees and Discounts” is the reason this image belongs at this point in “Help Sellers Buy Before They Sell and Keep the Listing.”
How a reader can use it
Use “Bridge Loan Costs Versus Cash-Home-Buyer Fees and Discounts” for its stated primary visual message job on “Help Sellers Buy Before They Sell and Keep the Listing.” Identify the claim, chart, comparison, process, property feature, or strategy shown and connect it to the exact decision the page addresses. The working notes for this panel should record the literal claim or comparison shown, the page fact it supports, the source behind that fact, and the decision the reader should make next. That record lets the reader identify whether the homeowner can move first while protecting the open-market listing and avoiding an unsupported promise about qualification or sale proceeds without asking this image to answer a different stage of the decision.
What still must be verified
“Bridge Loan Costs Versus Cash-Home-Buyer Fees and Discounts” organizes the primary visual message part of the decision; it does not settle the rest. The image does not approve financing, guarantee a sale, establish market value, remove contractual duties, or prove that one transition structure is best for every seller. The responsible next step after “Bridge Loan Costs Versus Cash-Home-Buyer Fees and Discounts” is to obtain the current document or finding that governs the issue and reconcile any difference before proceeding. On “Help Sellers Buy Before They Sell and Keep the Listing,” that safeguard applies specifically to the primary visual message role assigned to “Bridge Loan Costs Versus Cash-Home-Buyer Fees and Discounts.”
Move First, Then Prepare the Current Home for a Stronger Market Sale Image Overview
+ −What this image communicates
The “Move First, Then Prepare the Current Home for a Stronger Market Sale” image turns the central issue on “Help Sellers Buy Before They Sell and Keep the Listing” into a visible primary visual message. It is there to make one topic recognizable at a glance and give the reader a clear entry point into the deeper explanation on the page, while the page supplies the evidence and explanation needed to evaluate how equity, the current mortgage, next-home qualification, sale timing, liquidity, carrying costs, and backup plans interact. The visual centers “Move First, Then Prepare the Current Home for a Stronger Market Sale” on a specific housing or listing decision. It connects the visible promise to the property, the people involved, and the transaction sequence instead of leaving the message as abstract marketing. A useful reading separates what can be illustrated now from what still depends on the home's condition, the negotiated terms, verified financing, and current market response.
Why it belongs on this page
This Realtor-facing bridge resource explains how current-home equity can support the seller's next purchase while the agent keeps the listing. The primary visual message role of “Move First, Then Prepare the Current Home for a Stronger Market Sale” is the reason this image belongs at this point in “Help Sellers Buy Before They Sell and Keep the Listing.”
How a reader can use it
Use “Move First, Then Prepare the Current Home for a Stronger Market Sale” for its stated primary visual message job on “Help Sellers Buy Before They Sell and Keep the Listing.” Identify the claim, chart, comparison, process, property feature, or strategy shown and connect it to the exact decision the page addresses. The working notes for this panel should record the literal claim or comparison shown, the page fact it supports, the source behind that fact, and the decision the reader should make next. That record lets the reader identify whether the homeowner can move first while protecting the open-market listing and avoiding an unsupported promise about qualification or sale proceeds without asking this image to answer a different stage of the decision.
What still must be verified
The explanation around “Move First, Then Prepare the Current Home for a Stronger Market Sale” must remain inside the evidence available for this page. The image does not approve financing, guarantee a sale, establish market value, remove contractual duties, or prove that one transition structure is best for every seller. The “Move First, Then Prepare the Current Home for a Stronger Market Sale” visual supports a better-informed conversation, while the actual decision remains tied to current evidence and the people authorized to interpret it. On “Help Sellers Buy Before They Sell and Keep the Listing,” that safeguard applies specifically to the primary visual message role assigned to “Move First, Then Prepare the Current Home for a Stronger Market Sale.”
Six Benefits of Bridge Financing Before the Current Home Sells Image Overview
+ −What this image communicates
The purpose of “Six Benefits of Bridge Financing Before the Current Home Sells” is to organize one part of “Help Sellers Buy Before They Sell and Keep the Listing” around a primary visual message. It helps the reader understand how to make one topic recognizable at a glance and give the reader a clear entry point into the deeper explanation on the page and keeps the discussion centered on how equity, the current mortgage, next-home qualification, sale timing, liquidity, carrying costs, and backup plans interact. The visual centers “Six Benefits of Bridge Financing Before the Current Home Sells” on a specific housing or listing decision. It connects the visible promise to the property, the people involved, and the transaction sequence instead of leaving the message as abstract marketing. A useful reading separates what can be illustrated now from what still depends on the home's condition, the negotiated terms, verified financing, and current market response.
Why it belongs on this page
Its five images compare uses, lien and payment structures, costs versus cash-buyer discounts, move-first preparation, and six strategic benefits. The primary visual message role of “Six Benefits of Bridge Financing Before the Current Home Sells” is the reason this image belongs at this point in “Help Sellers Buy Before They Sell and Keep the Listing.”
The exact story carried by this graphic
The six-benefit panel should translate bridge financing into concrete seller outcomes: access equity, make a stronger next-home offer, move once, vacate before showings, prepare the current property, and preserve open-market exposure. Each benefit has a corresponding condition or risk—fees, liens, qualification, carrying exposure, delayed sale, repair cost, or lower-than-expected proceeds. Its value is a balanced checklist that lets the homeowner rank which benefit matters enough to justify the full structure.
How a reader can use it
Use “Six Benefits of Bridge Financing Before the Current Home Sells” for its stated primary visual message job on “Help Sellers Buy Before They Sell and Keep the Listing.” Identify the claim, chart, comparison, process, property feature, or strategy shown and connect it to the exact decision the page addresses. The working notes for this panel should record the literal claim or comparison shown, the page fact it supports, the source behind that fact, and the decision the reader should make next. That record lets the reader identify whether the homeowner can move first while protecting the open-market listing and avoiding an unsupported promise about qualification or sale proceeds without asking this image to answer a different stage of the decision.
What still must be verified
Keep the visual in its proper role. The image does not approve financing, guarantee a sale, establish market value, remove contractual duties, or prove that one transition structure is best for every seller. If a later disclosure, source update, appraisal, inspection, title item, program rule, or contract term conflicts with “Six Benefits of Bridge Financing Before the Current Home Sells,” the current controlling evidence takes priority. On “Help Sellers Buy Before They Sell and Keep the Listing,” that safeguard applies specifically to the primary visual message role assigned to “Six Benefits of Bridge Financing Before the Current Home Sells.”