Weekly Mortgage Market and Rate Update – August 3, 2026
Current Mortgage Rates Moved Higher, but Bonds Found Support
Updated August 3, 2026
What Is the Market Doing?
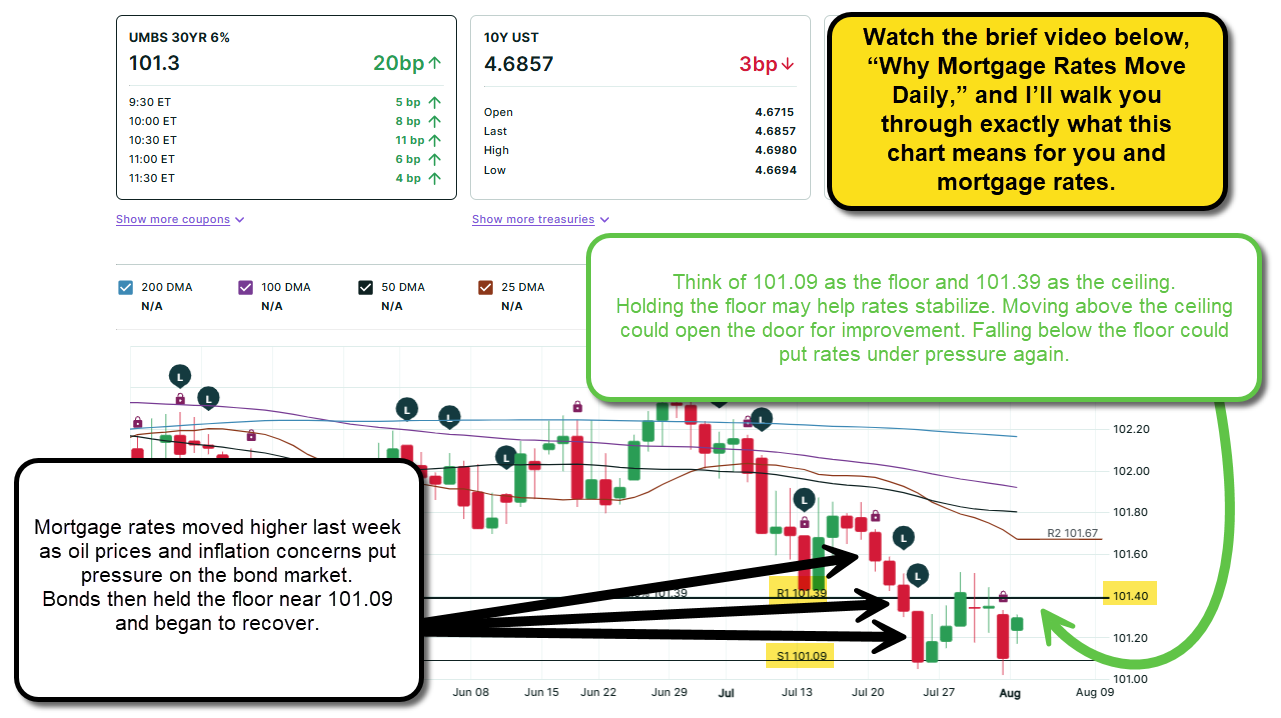
Mortgage rates moved higher last week. Rising oil prices, inflation concerns, and new fighting in the Middle East put pressure on the bond market.
The Federal Reserve left its short-term rate unchanged. However, three Fed members wanted a small rate increase. That told the market the Fed is still worried about inflation.
Freddie Mac’s July 30 weekly survey showed the average 30-year fixed rate rising from 6.58% to 6.66%.
This is a national survey average, not a personal rate quote. Actual rates and costs depend on the borrower, property, loan program, market, and timing.
Why did the market begin to improve?
Oil prices moved lower as the new week began. There were also signs that talks could reduce some of the conflict in the Middle East.
That helped mortgage bonds move higher and took some pressure off mortgage rates.
Mortgage bonds and mortgage rates usually move in opposite directions. When bonds improve, rates may get some relief. When bonds fall, rates may move higher.
What does the bond chart tell us?
Mortgage bonds held an important floor near 101.09.
Think of that level as the floor under the market. Holding the floor is a good sign, as it may help stabilize rates.
The first ceiling is near 101.39. Bonds need to move above that ceiling before rate conditions have more room to improve.
- Holding above 101.09 may help rates stabilize.
- Moving above 101.39 could open the door for lower rates.
- Falling below 101.09 could put rates under pressure again.
These are levels to watch, not promises about where rates will go.
What are we watching this week?
This is a big week for jobs reports. The market is watching private payrolls, jobless claims, wage growth, unemployment, and Friday’s national jobs report.
A weaker job market could help mortgage bonds and rates improve. Stronger hiring or faster wage growth could push rates higher.
We are also watching oil prices and the Middle East. A new jump in oil prices could quickly bring inflation concerns back.
Bottom line
Mortgage rates rose last week, but the bond chart shows some early improvement.
Bonds held the 101.09 floor and are trying to move toward the 101.39 ceiling. Jobs reports, oil prices, and world events may decide what happens next.
If you are wondering what these market changes mean for your plans, call or message me. I will help you understand what is happening without all the confusing market talk.
Mortgage Bond Market: Updated on 8-3-26
Mortgage Bond Market: Updated on 8-3-26
Watch the Trend, Not the Headline Rate
Below you’ll find the National Average Mortgage Rates as published for industry reference. These rates are for illustration only and reflect recently closed loans, not current market rates. Use this only for a general trend indicator. Your actual rate will depend on your financial profile and local market conditions, which is why getting pre-approved before you start shopping is key.
National Rate Averages
Historical Trend
Source: Optimal Blue Mortgage Market Indices (OBMMI). Indices reflect aggregate rate lock data. Learn more.
See What’s Happening: Locally & Nationally
The market moves fast. These two updates give you the clarity to stay ahead, so you can make confident, well-timed decisions, whether you’re buying, selling, or waiting.
MISSED A PREVIOUS WEEK'S UPDATE? CATCH UP HERE:
+ −Weekly Mortgage Market and Rate Update on 7-28-26
Weekly Mortgage Market and Rate Update on 7-22-26
Weekly Mortgage Market and Rate Update on 7-15-26
Weekly Mortgage Market and Rate Update on 7-7-26
Weekly Mortgage Market and Rate Update on 6-30-26
Weekly Mortgage Market and Rate Update on 6-23-26
Weekly Mortgage Market and Rate Update on 6-16-26
Weekly Mortgage Market and Rate Update on 6-9-26
Weekly Mortgage Market and Rate Update on 6-2-26
Weekly Mortgage Market and Rate Update on 5-26-26
Weekly Mortgage Market and Rate Update on 5-19-26
Weekly Mortgage Market and Rate Update on 5-12-26
Weekly Mortgage Market and Rate Update on 5-6-26
Weekly Mortgage Market and Rate Update on 4-27-26
Weekly Mortgage Market and Rate Update on 4-22-26
WE'RE HERE TO HELP
If you have any questions or need more information about our affordable home financing solutions, please don’t hesitate to CONTACT ME. My team and I are here to help you every step of the way!
Ready to start your home journey? Click here to submit your loan application today!
Best regards,
Michael Thayer, CMPS, CMA
NMLS #173264
Planet Home Lending, NMLS #17022
Explore Buyer & Seller Resources & Next Steps
+ −Market Timing vs. Market Strategy: When Is the Right Time to Buy... And More Importantly, Why?
Calculators & Loan Programs Questions Answered: Mortgage Programs & Financing Calculator
Smart Financing Strategies to Lower Your Monthly Mortgage Payment: Smart Mortgage Strategies & Financing Hacks
Homebuying Roadmap: Your Mortgage GPS
Moving To Middle Tennessee: Moving To Middle Tennessee Resource Center
Search Open Houses: View All Middle Tennessee Open Houses
Main Resource Hub: Buyers, Sellers, Realtors, and Builders Resources and Strategies
Video Transcripts
+ −Mortgage rates change every day, but most people don’t understand why… Or what it actually means for them. This page (updated weekly) is designed to simplify everything. In this video, you’ll learn:
- How to track mortgage rate trends
- What’s happening in the bond market
- The simple “teeter-totter” relationship between mortgage bonds and rates
- What’s driving rate movement (inflation, economic data, market reactions)
Whether you're:
- A homebuyer (first-time or moving up)
- A Realtor or builder advising clients
- A real estate investor
This resource helps you stay ahead of the market and make more confident decisions. You’ll also find:
- Local Nashville market data
- National housing trends
- Weekly outlooks on where rates may be heading next
Bookmark this page and check back weekly to stay informed.
- Go to: www.michaelthayer.com
- Scroll down to "Weekly Mortgage Market and Rate Update"
- Save the link to check back for the weekly updates.
Have questions or want a breakdown for your local market? Reach out; I am happy to help.
Why Rates Move Daily:
Alright, before we get into this, let me be very clear: if anyone is telling you mortgage rates move for some random reason or pointing to anything other than what I’m about to explain, they’re wrong; you’re talking to the wrong person. Mortgage rates are driven by two core factors: inflation and the economic data that impacts it, and more specifically, how those factors influence the way mortgage bonds trade on Wall Street. That’s what ultimately drives the rates you and I see every day, and it really is that simple. Some people point to the 10-year Treasury as an indicator, and while it can be helpful, it doesn’t always tell the full story and can be misleading at times. Most people can’t explain this clearly, and that’s why this exists: to break it down simply so you finally have clarity. It can feel confusing because it’s counterintuitive, but once you understand that it works in the opposite way you might expect, it becomes much easier. Think of it like a teeter-totter: when one side goes up, the other side comes down, and that’s exactly how mortgage bonds and mortgage rates behave. What you’re looking at in a bond chart is daily movements shown as candlesticks; each bar represents one full day of trading. Green is good, meaning bonds improved and rates typically move lower; red is bad, meaning bonds declined and rates move higher. Now tie that back to the teeter-totter. When bond yields improve, rates get better; when bond yields decline, rates get worse. The biggest factor influencing all of this is inflation, because inflation erodes the value of bonds over time. When inflation rises or is expected to rise, bonds struggle, and when bonds struggle, mortgage rates increase. When inflation cools, bonds improve, and rates can move lower. So if you’re watching one thing, watch inflation; it’s the key driver. If inflation comes in higher than expected, expect rates to rise; if it cools, rates can improve. The good news is you don’t have to figure this out on your own. I break this down and update it every week, so you can understand the trend, see what’s happening, and make better decisions. Most people fear what they don’t understand, and that costs them money, but when you have clarity, you make stronger, more confident decisions. Use this as your resource, come back to it, and if you have questions, reach out. I’m here to help make sense of it all.
Additional Information & Reference Guides
+ −Mortgage Bond Market: Updated on 8-3-26 Image Overview
+ −What this image communicates
The “Mortgage Bond Market: Updated on 8-3-26” image turns the central issue on “Weekly Mortgage Market and Rate Update – August 3, 2026” into a visible primary visual message. It is there to make one topic recognizable at a glance and give the reader a clear entry point into the deeper explanation on the page, while the page supplies the evidence and explanation needed to evaluate how the reported bond-market or rate environment affects payment planning without treating a dated snapshot as a live quote. The image makes “Mortgage Bond Market: Updated on 8-3-26” the dominant visual message and gives the reader a defined entry point into the page's argument. The wording identifies what deserves attention first; the surrounding design establishes whether the reader is looking at a claim, a choice, a sequence, or a practical resource. That distinction determines what evidence should be gathered before the message is applied.
Why it belongs on this page
The August 3 update reports Freddie Mac's national 30-year average rising from 6.58% to 6.66% after oil, inflation concern, Middle East conflict, and a divided Federal Reserve pressured bonds. As oil eased, mortgage bonds held support near 101.09 and faced resistance near 101.39. The image should explain those dated levels and the possibility of stabilization without turning them into a loan quote or guaranteed market floor. The primary visual message role of “Mortgage Bond Market: Updated on 8-3-26” is the reason this image belongs at this point in “Weekly Mortgage Market and Rate Update – August 3, 2026.”
The exact story carried by this graphic
The August 3, 2026 image captures the mortgage-bond-market setting at the opening of a new month. Its date separates this update from the July record and from any later August repricing. The useful question is whether the borrower's transaction timeline can tolerate movement between the snapshot date and the required lock or closing date. Readers should pair the chart with current lender pricing, the remaining economic calendar, and the cost of changing the rate or points rather than using the graphic as a quote. The image is historical context for an August 3 conversation; its figures require a fresh live check before any financing decision.
The support-and-resistance levels make this August 3 chart materially different from a general market summary. Holding near 101.09 described the immediate floor in mortgage bonds, while 101.39 was the first ceiling that needed to break before the technical picture could improve. Those levels can fail or move after publication. Their benefit is showing what the market was testing at that moment, not creating a permanent lock recommendation.
How a reader can use it
Use “Mortgage Bond Market: Updated on 8-3-26” for its stated primary visual message job on “Weekly Mortgage Market and Rate Update – August 3, 2026.” Identify the claim, chart, comparison, process, property feature, or strategy shown and connect it to the exact decision the page addresses. The working notes for this panel should record the literal claim or comparison shown, the page fact it supports, the source behind that fact, and the decision the reader should make next. That record lets the reader separate a market explanation from the rate and costs available to one borrower for one property without asking this image to answer a different stage of the decision.
What still must be verified
The boundary is important. A dated market image cannot guarantee a future rate, reproduce a Loan Estimate, or show the pricing adjustments attached to a particular credit, occupancy, property, loan amount, or lock period. The “Mortgage Bond Market: Updated on 8-3-26” image can improve preparation and questions, but it cannot replace the records, disclosures, findings, approvals, or agreements issued for the actual borrower, property, and transaction. On “Weekly Mortgage Market and Rate Update – August 3, 2026,” that safeguard applies specifically to the primary visual message role assigned to “Mortgage Bond Market: Updated on 8-3-26.”