Buy Your Next Home Before Selling Your Current One
Don’t Let The Home You’re Selling Cost You The Home You Want.
You may have the income, credit, and down payment to buy your next home.
But if the mortgage on your current home is still being counted against you, it can skew the numbers and prevent you from qualifying.
You may not have an affordability problem. You may have a qualification problem.
One acceptable offer on your current home could change the entire equation.
What If You Didn’t Have To Wait For Your Current Home To Sell?
That’s where the Purchase EDGE Guarantee can help.
We create a qualifying purchase offer on your current home.
When applicable underwriting requirements are met, our underwriter will exclude your departing residence mortgage payment from your debt-to-income calculation used to qualify you for your next home.
The house you’re leaving may no longer have to stand between you and the house you want.
Four Steps to Qualify for the Next Home Before Selling
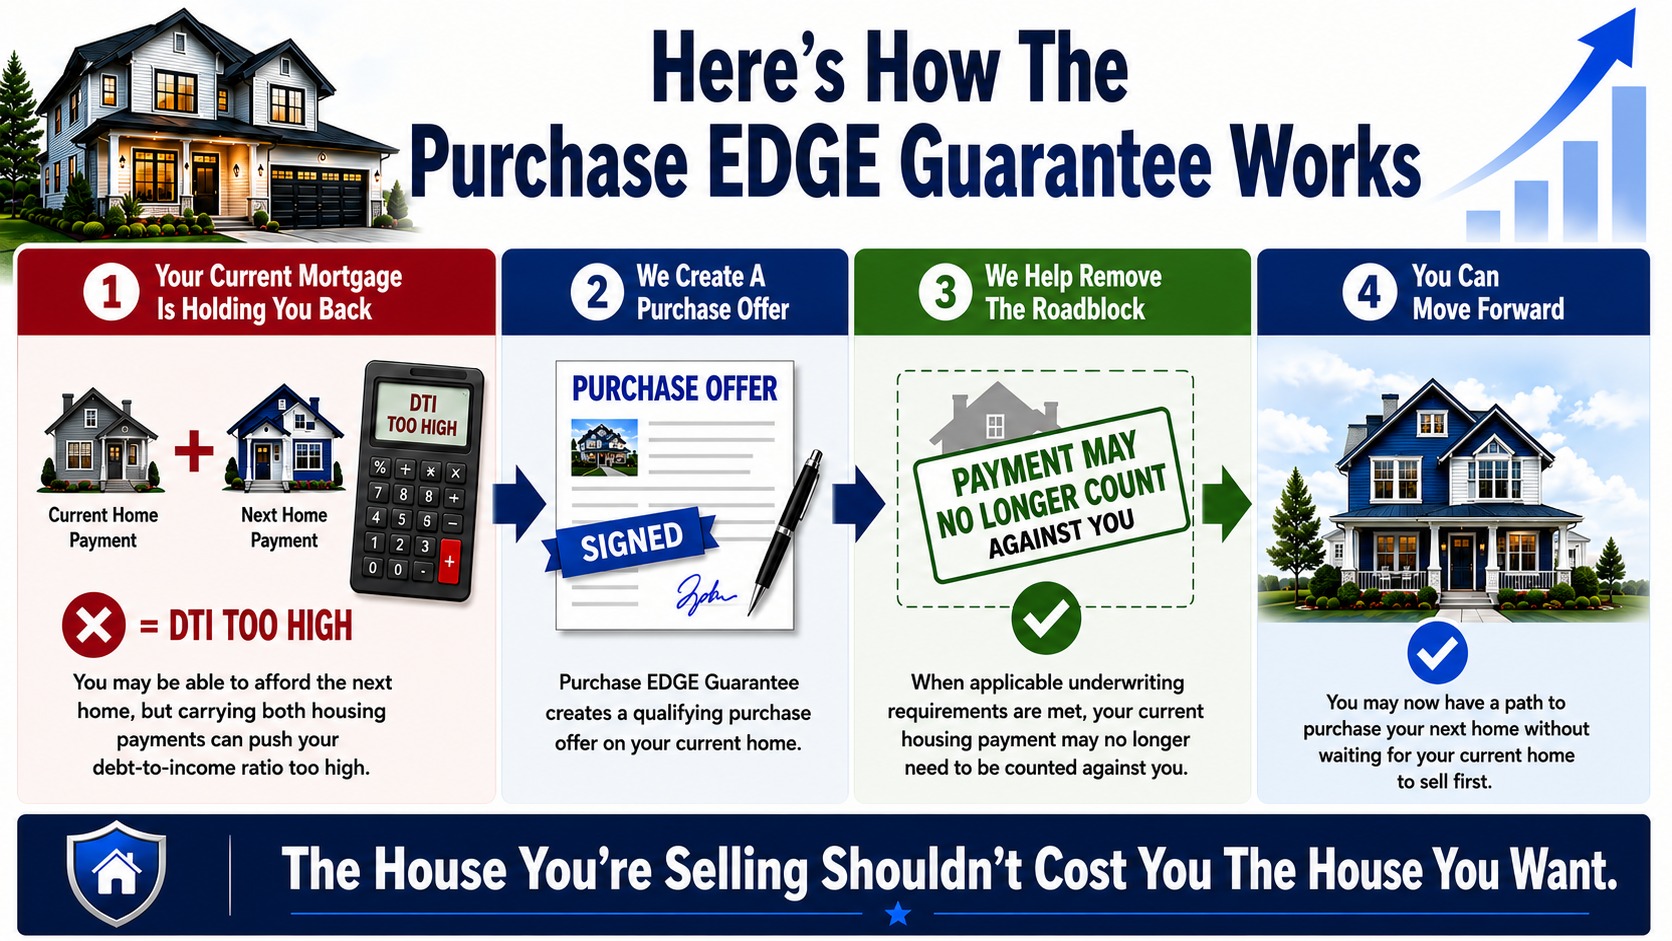
Four Steps to Qualify for the Next Home Before Selling
What If $3,500 Could Keep You From Losing The Home You Actually Want?
The Purchase EDGE Guarantee costs $3,500 and is not due until you close the sale of your departing residence.
Not a percentage of your home’s sales price.
Your current home stays on the market, and you continue trying to sell it.
Now you can qualify for your next home and are no longer forced to wait for your current/departing residence to sell and close.
Our Purchase Edge Guarantee is the difference between waiting to sell your current home and moving forward on your new home.
The $3,500 Purchase EDGE Cost Versus the Cost of Waiting
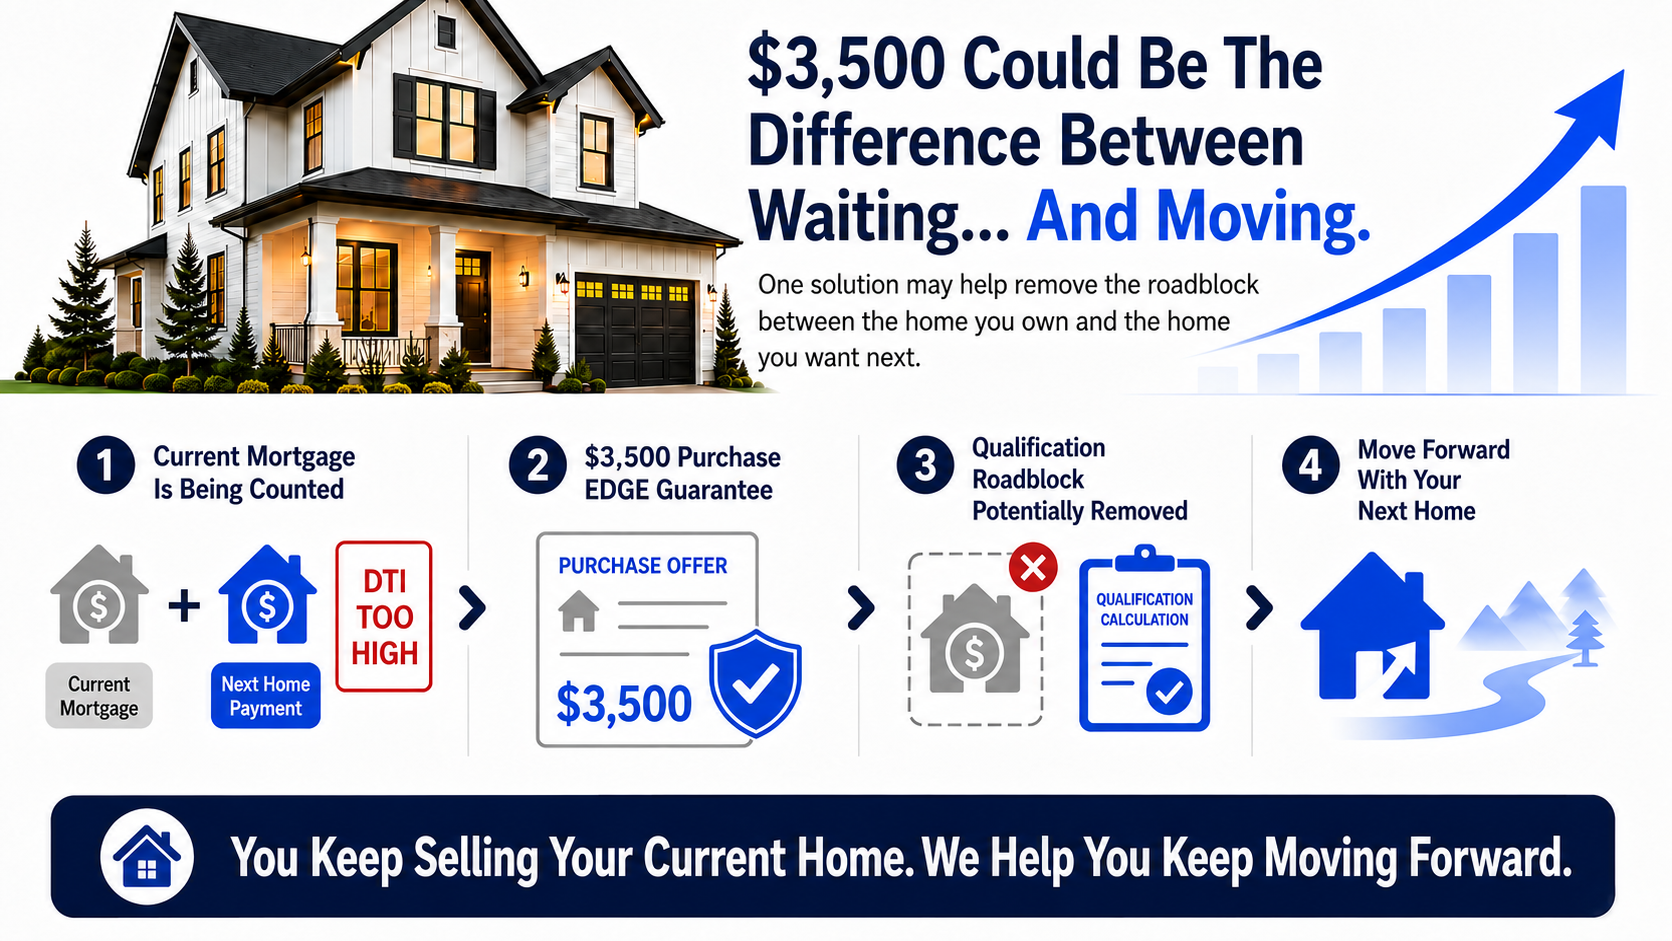
The $3,500 Purchase EDGE Cost Versus the Cost of Waiting
Before You Give Up Any Equity, See What The Numbers Say
Before You Give Up Any Equity, See What The Numbers Say
So Why Does This Only Cost $3,500?
Because our goal isn’t to make money buying your current home.
Our goal is to help finance your next one.
You keep trying to sell your current home normally.
We help solve the qualification roadblock that may be preventing you from moving forward.
You sell the current home. We help finance the next one.
It really is that simple.
Keep Selling the Current Home While Removing the Qualification Roadblock
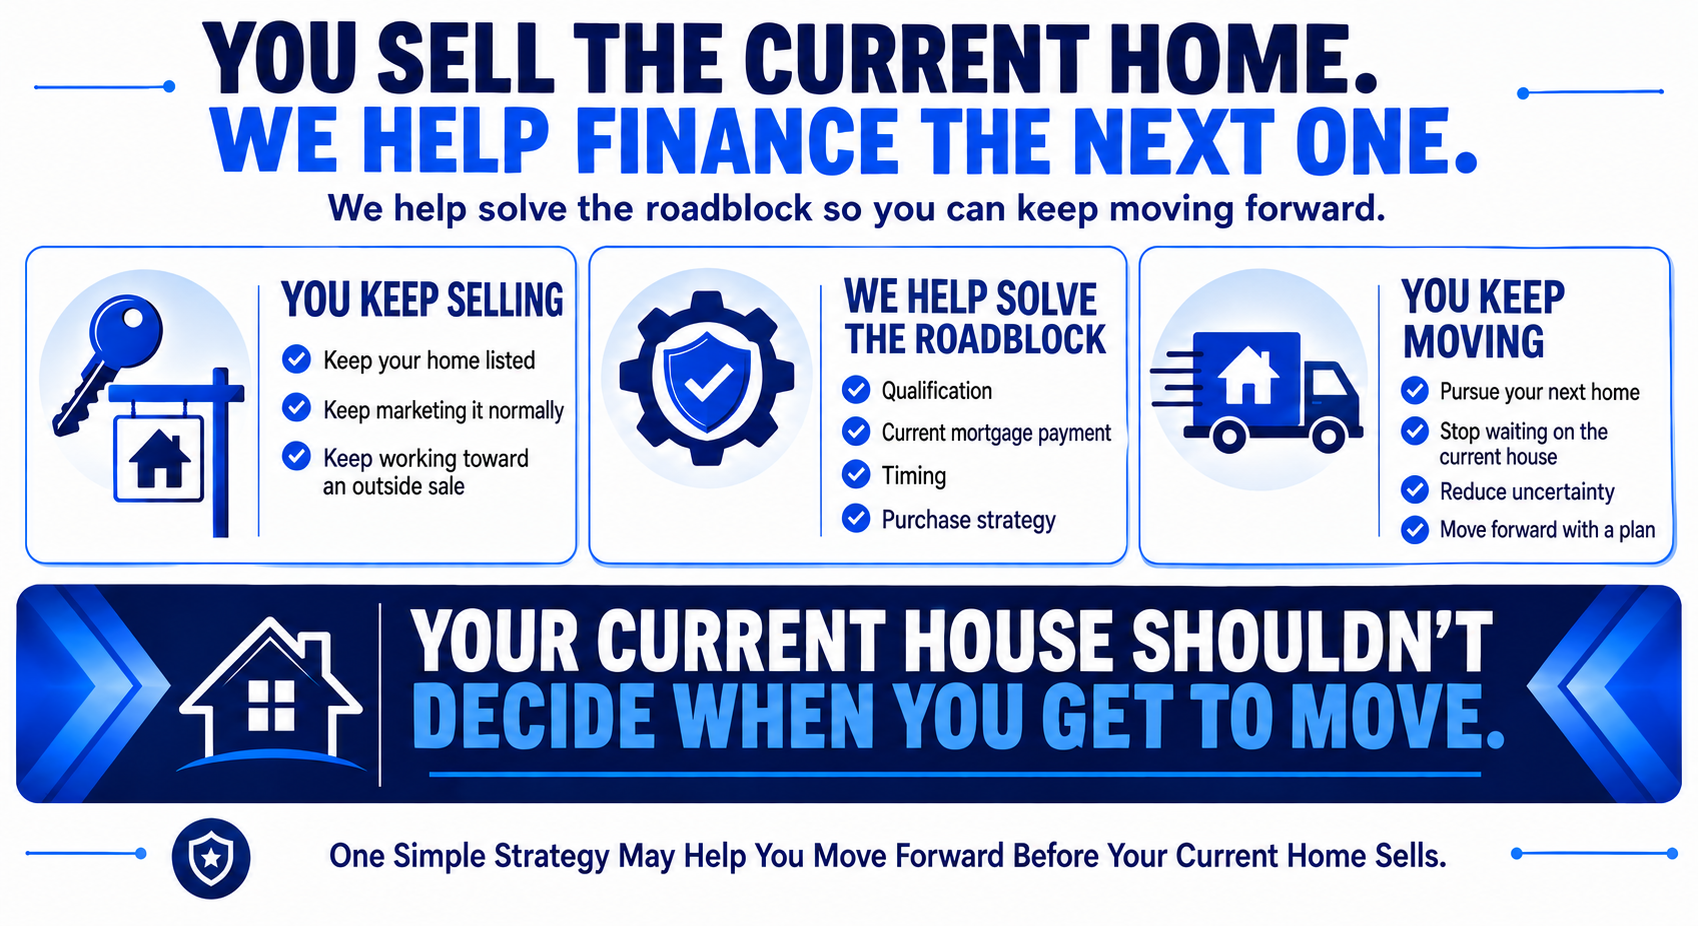
Keep Selling the Current Home While Removing the Qualification Roadblock
Don’t Lose The Next Home Because Of The One You’re Already Trying To Sell.
Send me the address of your current home and tell me what you’re trying to buy next.
I’ll review the numbers and determine whether the $3,500 Purchase EDGE Guarantee could help remove the qualification roadblock and provide a path forward.
➡️ Call or Text Michael @ 615-585-5900
Prefer to put a time on the calendar?
➡️ Schedule a 10-Minute Homebuyer Strategy Review
No presentation. No obligation. Just the numbers and whether there’s a smarter way to make your move.
Explore Other Ways To Move Before You Sell
Every situation is different. Explore these related strategies designed to create more flexibility, remove common roadblocks, and make the next move easier.
Explore the No-Payment Bridge Loan
- Access equity from the current home before it sells, create funds for the next purchase, and gain more flexibility over the timing of the move.
See How The Purchase EDGE Guarantee Works
- Resolve a qualification roadblock caused by the mortgage on the current home that is preventing the next purchase from proceeding.
Explore Purchase EDGE & The Guaranteed Backup Offer
- Keep the current home on the market while having a guaranteed backup buyer available if greater certainty is needed.
Best regards,
Michael Thayer, CMPS, CMA
Planet Home Lending
NMLS #173264 | Company NMLS #17022
Explore Buyer & Seller Resources & Next Steps
+ −Market Timing vs. Market Strategy: When Is the Right Time to Buy... And More Importantly, Why?
Calculators & Loan Programs Questions Answered: Mortgage Programs & Financing Calculator
Smart Financing Strategies to Lower Your Monthly Mortgage Payment: Smart Mortgage Strategies & Financing Hacks
Homebuying Roadmap: Your Mortgage GPS
Moving To Middle Tennessee: Moving To Middle Tennessee Resource Center
Search Open Houses: View All Middle Tennessee Open Houses
Main Resource Hub: Buyers, Sellers, Realtors, and Builders Resources and Strategies
Additional Information & Reference Guides
+ −Video Transcript
+ −00:00
You found the new home that you want, but your current home could prevent you from buying the new home.
00:06
You've got good income. You've got great credit. You even have your down payment money. Everything looks right.
00:12
But your current house hasn't sold yet.
00:15
So when both mortgage payments are counted against you, suddenly, you're being told you don't qualify.
00:20
Not because you can't afford the home, because the mortgage on your current house
00:25
That you're trying to sell is still standing in your way.
00:28
Before you risk losing that house you want.
00:30
You need to understand this first. With our Purchase Edge guarantee, we write an offer to buy your current house.
00:37
That allows our underwriter to exclude the mortgage payment from your current home, from your debt-to-income ratio, helping you qualify for the next house that you want to buy.
00:46
Your current house stays listed. You keep selling it like you normally would. And the cost? It's just a flat $3,500. That's not due until you close on the sale of your current home.
00:57
So before you delay your next move, settle for another house, or watch someone else buy the house you want. Stop!
01:04
Use the calculator below. Run the numbers first.
01:08
Don't let the house you're trying to sell prevent you from buying the house you want. Send me the address. Let's create a path forward, and the solutions you need to move forward with confidence. We'll talk to you soon.
Four Steps to Qualify for the Next Home Before Selling Image Overview
+ −What this image communicates
“Four Steps to Qualify for the Next Home Before Selling” is not a decorative break in “Buy Your Next Home Before Selling Your Current One.” It is the page's primary visual message, designed to make one topic recognizable at a glance and give the reader a clear entry point into the deeper explanation on the page. That framing matters because the reader is evaluating how equity, the current mortgage, next-home qualification, sale timing, liquidity, carrying costs, and backup plans interact. The visual presents “Four Steps to Qualify for the Next Home Before Selling” as a sequence with dependencies. Its order matters: one confirmed input creates the next task, and an unresolved item can stop the file, listing, or purchase from advancing. By turning the process into visible stages, the graphic lets a reader identify the current position, the next handoff, and the deadline or evidence that controls progress.
Why it belongs on this page
This Purchase EDGE page lays out four steps for qualifying on the next home before the current one sells, compares a stated $3,500 program cost with the cost of delay, and shows how the present listing can continue. The primary visual message role of “Four Steps to Qualify for the Next Home Before Selling” is the reason this image belongs at this point in “Buy Your Next Home Before Selling Your Current One.”
How a reader can use it
Use “Four Steps to Qualify for the Next Home Before Selling” for its stated primary visual message job on “Buy Your Next Home Before Selling Your Current One.” Identify the claim, chart, comparison, process, property feature, or strategy shown and connect it to the exact decision the page addresses. The working notes for this panel should record the literal claim or comparison shown, the page fact it supports, the source behind that fact, and the decision the reader should make next. That record lets the reader identify whether the homeowner can move first while protecting the open-market listing and avoiding an unsupported promise about qualification or sale proceeds without asking this image to answer a different stage of the decision.
What still must be verified
The final safeguard is verification. The image does not approve financing, guarantee a sale, establish market value, remove contractual duties, or prove that one transition structure is best for every seller. A reader should leave “Four Steps to Qualify for the Next Home Before Selling” knowing what to ask and what to gather—not believing that a graphic has already supplied an approval, valuation, legal conclusion, or guaranteed outcome. On “Buy Your Next Home Before Selling Your Current One,” that safeguard applies specifically to the primary visual message role assigned to “Four Steps to Qualify for the Next Home Before Selling.”
The $3,500 Purchase EDGE Cost Versus the Cost of Waiting Image Overview
+ −What this image communicates
The “The $3,500 Purchase EDGE Cost Versus the Cost of Waiting” image turns the central issue on “Buy Your Next Home Before Selling Your Current One” into a visible primary visual message. It is there to make one topic recognizable at a glance and give the reader a clear entry point into the deeper explanation on the page, while the page supplies the evidence and explanation needed to evaluate how equity, the current mortgage, next-home qualification, sale timing, liquidity, carrying costs, and backup plans interact. The visual uses a side-by-side comparison to separate “The $3,500 Purchase EDGE Cost Versus the Cost of Waiting” into alternatives that should not be treated as interchangeable. Its layout asks the reader to compare structure, cost, timing, eligibility, and consequence—not select a winner from one headline number. The comparison is therefore a decision aid, with each column pointing to a different fact that must be confirmed.
Why it belongs on this page
The images should help a homeowner compare contract timing, program conditions, backup terms, net proceeds, carrying exposure, agent responsibilities, and the value of preserved market upside. The primary visual message role of “The $3,500 Purchase EDGE Cost Versus the Cost of Waiting” is the reason this image belongs at this point in “Buy Your Next Home Before Selling Your Current One.”
How a reader can use it
Use “The $3,500 Purchase EDGE Cost Versus the Cost of Waiting” for its stated primary visual message job on “Buy Your Next Home Before Selling Your Current One.” Identify the claim, chart, comparison, process, property feature, or strategy shown and connect it to the exact decision the page addresses. The working notes for this panel should record the literal claim or comparison shown, the page fact it supports, the source behind that fact, and the decision the reader should make next. That record lets the reader identify whether the homeowner can move first while protecting the open-market listing and avoiding an unsupported promise about qualification or sale proceeds without asking this image to answer a different stage of the decision.
What still must be verified
“The $3,500 Purchase EDGE Cost Versus the Cost of Waiting” organizes the primary visual message part of the decision; it does not settle the rest. The image does not approve financing, guarantee a sale, establish market value, remove contractual duties, or prove that one transition structure is best for every seller. The responsible next step after “The $3,500 Purchase EDGE Cost Versus the Cost of Waiting” is to obtain the current document or finding that governs the issue and reconcile any difference before proceeding. On “Buy Your Next Home Before Selling Your Current One,” that safeguard applies specifically to the primary visual message role assigned to “The $3,500 Purchase EDGE Cost Versus the Cost of Waiting.”
Keep Selling the Current Home While Removing the Qualification Roadblock Image Overview
+ −What the listing-preservation image shows
“Keep Selling the Current Home While Removing the Qualification Roadblock” separates two jobs that often become tangled. The Realtor continues to price, present, market, show, and negotiate the current property. The mortgage or Purchase EDGE structure addresses whether the seller can qualify for and close on the next home before the current sale is complete. The image's message is that solving the financing sequence does not require abandoning the listing or transferring the seller relationship away from the agent.
Why this matters on the Purchase EDGE page
On “Buy Your Next Home Before Selling Your Current One,” the seller is comparing control with timing risk. Preserving the listing may protect open-market upside and professional representation, while the backup or guarantee may reduce uncertainty around the next purchase. The reader benefit is optionality with named rules: the seller can understand what continues in the listing lane, what changes in the financing lane, and which decision dates connect them.
How the seller, agent, and mortgage team use it
Document the next-home contract dates, current-home listing plan, qualification treatment, Purchase EDGE eligibility, backup amount or terms, fees, property conditions, decision deadlines, and communication owners. Track market response and any listing or contract change that could affect the program. Confirm who will notify the other participants before an option expires. A useful plan also states the fallback if the property sells later or nets less than expected, so the seller understands carrying exposure and repayment rather than relying on the hoped-for outcome.
What the image does not guarantee
The visual does not promise Purchase EDGE eligibility, next-home approval, a sale price, a buyer, a closing date, appraisal, title, property condition, or a particular net proceed. It does not alter the listing agreement or the Realtor's duties. Signed program documents, loan disclosures, underwriting, contracts, title findings, and current property evidence control the result. Any change in price, contract, debt, income, assets, property, or timing requires the coordinated plan to be reviewed again.