Sixth Stop: Processing & Final Underwriting Approval
Let’s Complete The Final Loan Review And Prepare Everything Needed For Closing Day
Now that you’re under contract and many of the initial financing steps have already been completed, the next stage focuses on submitting the remaining property and contract documentation to underwriting for final review.
This stage is designed to help finalize your loan approval, satisfy any remaining underwriting conditions, and prepare your file for Clear To Close.
Mortgage GPS Roadmap — Core Strategy and Decision Context
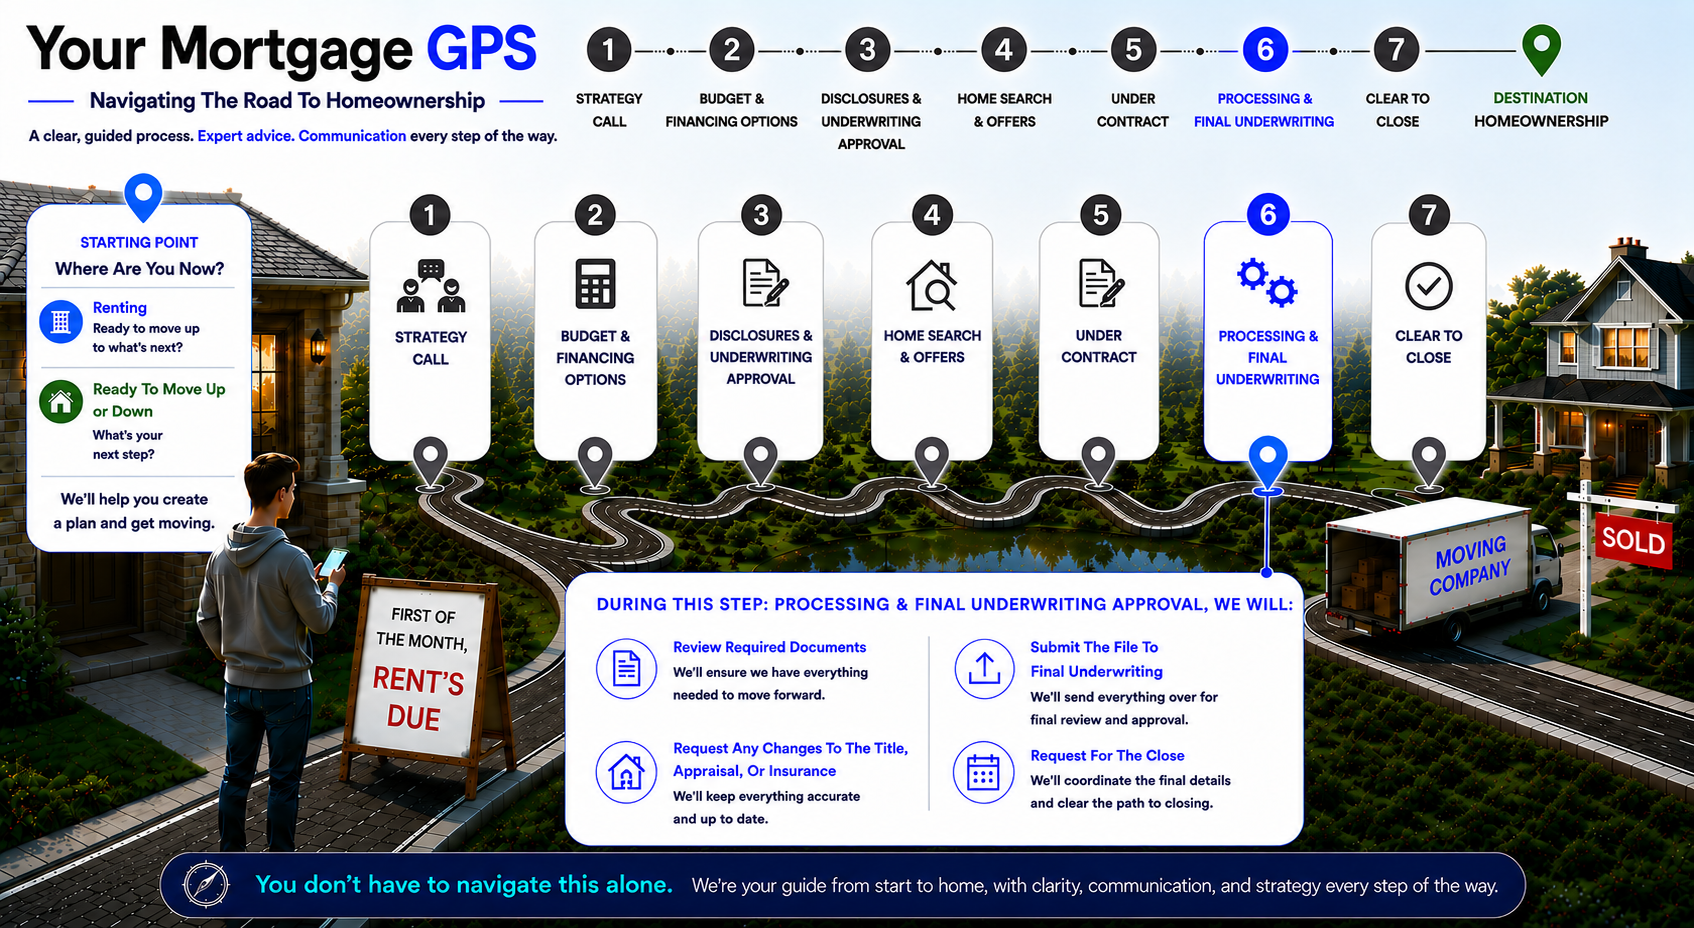
Mortgage GPS Roadmap — Core Strategy and Decision Context
What We Cover During Processing & Final Underwriting
➡️ Reviewing The Appraisal & Title Work
- Underwriting will review the completed appraisal, title report, and supporting property documentation as part of the final approval process.
- You will receive a copy of the completed appraisal for your records, and federal lending regulations require borrowers to acknowledge receipt of the appraisal as part of the loan approval process.
➡️ Verifying Homeowners Insurance Coverage
- We’ll confirm your homeowners' insurance coverage and policy information prior to closing.
➡️ Submitting Final Documentation To Underwriting
- We’ll provide underwriting with the remaining documents related to the property, contract, title work, appraisal, homeowners' insurance, and any updated financial documentation needed for final review.
➡️ Reviewing Any Remaining Underwriting Conditions
- As underwriting reviews newly submitted items, such as the appraisal, title work, homeowners insurance, and updated documentation, it may occasionally request additional information or clarification regarding items being reviewed for the first time as part of the final approval process.
➡️ Reviewing & Signing Your Initial Closing Disclosure
- Federal regulations require borrowers to acknowledge and sign the Initial Closing Disclosure at least three (3) business days prior to closing before final loan documents can be completed.
- The initial Closing Disclosure may contain estimated figures that are subject to change prior to closing as final numbers are reviewed, balanced, and verified by the title company, lender, and other parties involved in the transaction.
➡️ Preparing For Final Loan Approval
- Once all remaining underwriting conditions have been satisfied, your final loan approval will be issued, also known as your “Clear To Close,” meaning your loan is officially ready for closing day.
What Can You Expect During Processing And Final Underwriting — How the Process Works in Practice
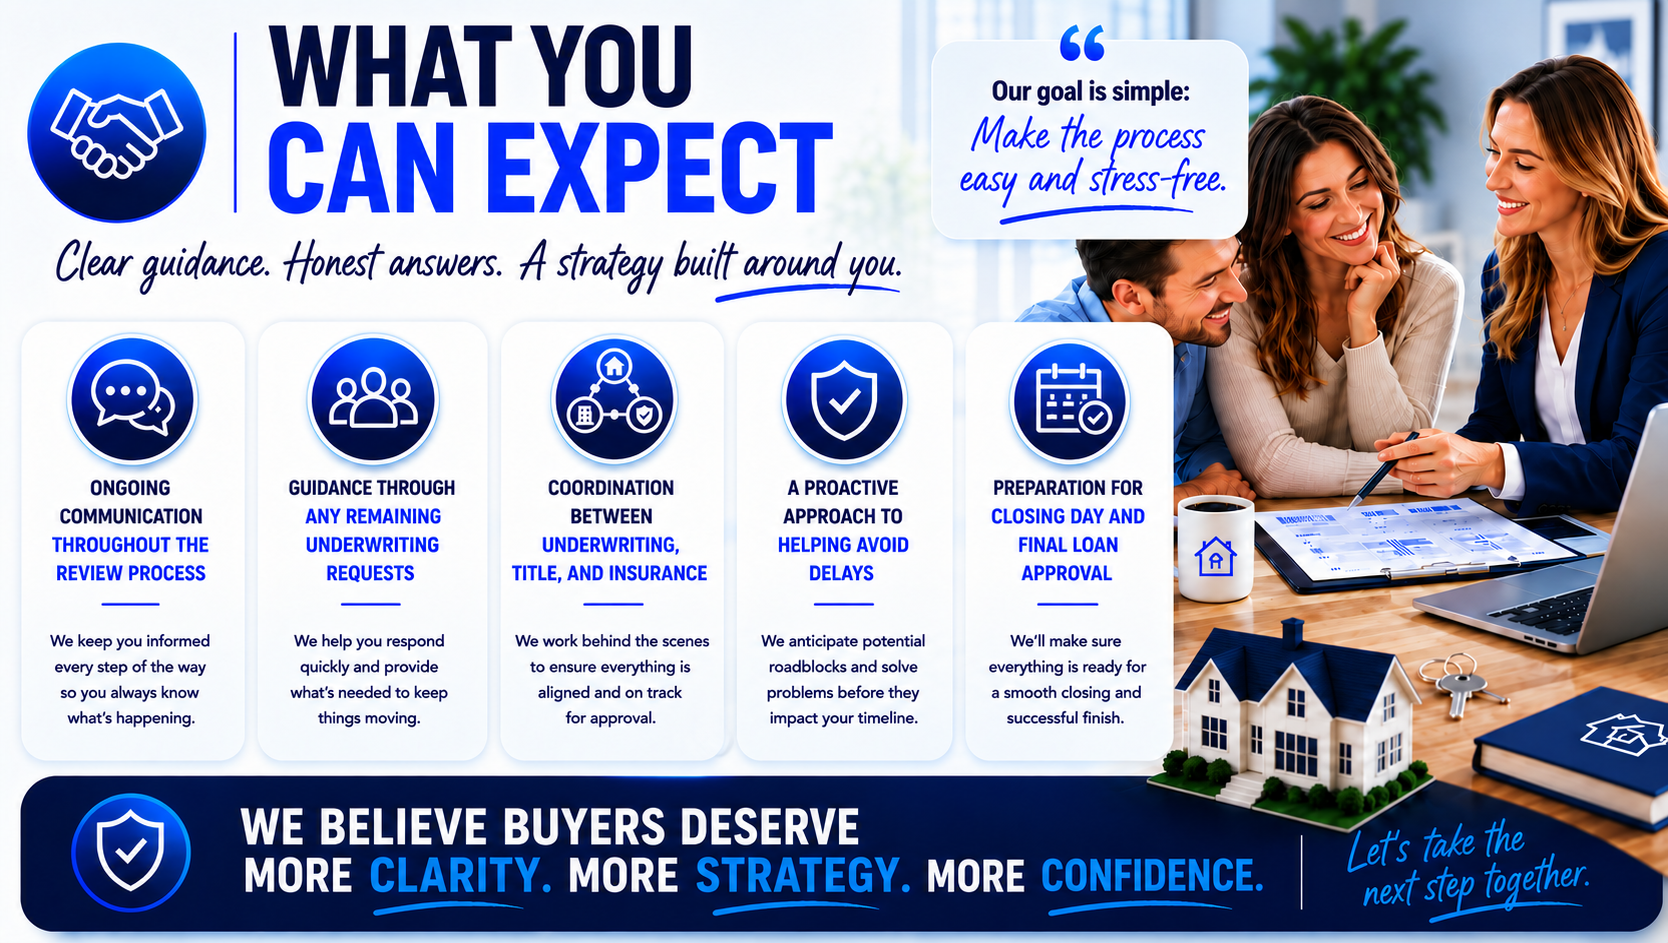
What Can You Expect During Processing And Final Underwriting — How the Process Works in Practice
This Is About Finalizing The Details
At this stage, most of the major financing and underwriting work has already been completed.
Our goal is to help keep everything organized, satisfy any remaining conditions quickly, and move your loan smoothly toward final approval and closing day.
Click On Any Step Below To Learn More About Your Mortgage Journey
➡️ Step #1 - Initial Strategy Call
➡️ Step #2 - Budget & Financing Options
➡️ Step #3 - Initial Loan Disclosures & Underwriting Approval
➡️ Step #4 - Home Search & Offers
We’re Here To Help Every Step Of The Way
Whether you’re preparing for the next stage of the process, reviewing financing options, or simply have questions along the way, my team and I are here to guide you with clarity and confidence.
Clear communication matters, and we want you to feel informed and supported throughout every step of your homeownership journey.
➡️ Have Questions? Contact Our Team Here
Best regards,
Michael Thayer, CMPS, CMA
NMLS #173264
Planet Home Lending, NMLS #17022
Explore Buyer & Seller Resources & Next Steps
+ −Market Timing vs. Market Strategy: When Is the Right Time to Buy... And More Importantly, Why?
Calculators & Loan Programs Questions Answered: Mortgage Programs & Financing Calculator
Smart Financing Strategies to Lower Your Monthly Mortgage Payment: Smart Mortgage Strategies & Financing Hacks
Homebuying Roadmap: Your Mortgage GPS
Moving To Middle Tennessee: Moving To Middle Tennessee Resource Center
Search Open Houses: View All Middle Tennessee Open Houses
Main Resource Hub: Buyers, Sellers, Realtors, and Builders Resources and Strategies
Additional Information & Reference Guides
+ −Welcome Video Transcript
+ −Video Transcript
00:00
Welcome to stop number 6 of your Mortgage GPS, processing and final underwriting approval. At this stage of the process, the good news is, you're almost there. We've completed the heavy lifting, the strategy's already been built, the finances have already been reviewed. Underwriting has already reviewed and signed off on your file, and we know you qualify. That's exactly why we follow the Mortgage GPS.
00:19
Most of the work happened before you even went under contract. Now, we're simply working through the final details needed to get your file to the closing tape.
00:27
I'm Michael Thayer, mortgage advisor based in Nashville, Tennessee, serving clients nationwide. At this stage, my team and I are working behind the scenes to finalize everything that's needed for closing. Things like final underwriting review, updating documents if needed to bring your file current.
00:41
Title and insurance verifications, final numbers for closing, and making sure everything required has been satisfied. The good news is, most buyers are surprised by how little they actually need to do during this stage.
00:54
Now, our job is just to keep everything organized, communicate updates along the way, and make sure nothing falls through the cracks. Because the finish line is in sight, and before long.
01:04
We'll be celebrating your clear clothes.
01:06
When you're ready, let's move to step 7, clear to close, we'll talk to you soon.
Mortgage GPS Roadmap — Core Strategy and Decision Context Image Overview
+ −What this image communicates
On “Sixth Stop: Processing & Final Underwriting Approval,” the “Mortgage GPS Roadmap — Core Strategy and Decision Context” visual isolates one decision from a larger housing conversation. As a central strategy, it is meant to state the main tension clearly and show which decision should be made before secondary details distract from it. The subject belongs to mortgage-process roadmap, where the useful question is what must happen at this stage, who owns the next action, and which conditions must be resolved before the file can advance. The visual presents “Mortgage GPS Roadmap” as a sequence with dependencies. Its order matters: one confirmed input creates the next task, and an unresolved item can stop the file, listing, or purchase from advancing. By turning the process into visible stages, the graphic lets a reader identify the current position, the next handoff, and the deadline or evidence that controls progress.
Why it belongs on this page
The sixth Mortgage GPS stop covers processing and final underwriting. The central strategy role of “Mortgage GPS Roadmap” is the reason this image belongs at this point in “Sixth Stop: Processing & Final Underwriting Approval.”
The exact story carried by this graphic
At the sixth stop, the Mortgage GPS roadmap positions the file after contract acceptance but before final underwriting approval. Processing is assembling and reconciling the record: updated borrower documents, appraisal, title, insurance, contract changes, verifications, and prior conditions. This visual should reduce the false sense that silence means completion. The useful question is which conditions remain open, who owns each response, and whether any new financial or property change must be disclosed before the underwriter can make the final decision.
How a reader can use it
Use “Mortgage GPS Roadmap” for its stated central strategy job on “Sixth Stop: Processing & Final Underwriting Approval.” Name the desired outcome, identify the constraint that could block it, and decide which evidence would change the answer. The working notes for this panel should record the desired result, the assumption carrying the most risk, the fact that would disprove it, and the decision that must be made first. That record lets the reader see the sequence early enough to prevent a missing document or misunderstood responsibility from becoming a closing problem without asking this image to answer a different stage of the decision.
What still must be verified
The final safeguard is verification. A process graphic cannot promise an identical timeline; loan type, borrower documentation, property findings, third parties, contract terms, and underwriting can change the order or timing. A reader should leave “Mortgage GPS Roadmap — Core Strategy and Decision Context” knowing what to ask and what to gather—not believing that a graphic has already supplied an approval, valuation, legal conclusion, or guaranteed outcome. On “Sixth Stop: Processing & Final Underwriting Approval,” that safeguard applies specifically to the central strategy role assigned to “Mortgage GPS Roadmap.”
What Can You Expect During Processing And Final Underwriting — How the Process Works in Practice Image Overview
+ −What this image communicates
“What Can You Expect During Processing And Final Underwriting — How the Process Works in Practice” is not a decorative break in “Sixth Stop: Processing & Final Underwriting Approval.” It is the page's working sequence, designed to show the order of operations, the handoff between people, and the checkpoint that determines whether the next step is ready. That framing matters because the reader is evaluating what must happen at this stage, who owns the next action, and which conditions must be resolved before the file can advance. The visual presents “What Can You Expect During Processing And Final Underwriting” as a sequence with dependencies. Its order matters: one confirmed input creates the next task, and an unresolved item can stop the file, listing, or purchase from advancing. By turning the process into visible stages, the graphic lets a reader identify the current position, the next handoff, and the deadline or evidence that controls progress.
Why it belongs on this page
The roadmap image locates the borrower late in the sequence, while the process image explains document refreshes, appraisal and title review, insurance, verification of conditions, and the underwriter's final evaluation. The working sequence role of “What Can You Expect During Processing And Final Underwriting” is the reason this image belongs at this point in “Sixth Stop: Processing & Final Underwriting Approval.”
The processing-and-final-underwriting panel is a reconciliation process. The processor assembles the current application, contract, appraisal, title, insurance, verifications, and borrower documents; the underwriter reviews whether prior conditions are satisfied and whether anything changed. Each condition needs an owner and status, and every refreshed document needs a clear as-of date. The panel benefits the borrower by showing why a last request may be evidence of a file being completed, not proof that the lender forgot earlier records.
How a reader can use it
Use “What Can You Expect During Processing And Final Underwriting” for its stated working sequence job on “Sixth Stop: Processing & Final Underwriting Approval.” Read the visual from the first confirmed fact through the next action, noting dependencies, deadlines, and the owner of each task. The working notes for this panel should record the starting condition, each dependent step, the responsible person, the handoff document, the deadline, and the condition required to advance. That record lets the reader see the sequence early enough to prevent a missing document or misunderstood responsibility from becoming a closing problem without asking this image to answer a different stage of the decision.
What still must be verified
The explanation around “What Can You Expect During Processing And Final Underwriting” must remain inside the evidence available for this page. A process graphic cannot promise an identical timeline; loan type, borrower documentation, property findings, third parties, contract terms, and underwriting can change the order or timing. The “What Can You Expect During Processing And Final Underwriting — How the Process Works in Practice” visual supports a better-informed conversation, while the actual decision remains tied to current evidence and the people authorized to interpret it. On “Sixth Stop: Processing & Final Underwriting Approval,” that safeguard applies specifically to the working sequence role assigned to “What Can You Expect During Processing And Final Underwriting.”