Weekly Mortgage Market and Rate Update – October 13, 2026
Mortgage Rates Moved Higher, but the Bond Market Is Improving
Updated October 13, 2026
What Is the Market Doing?
Mortgage rates rose in the latest national survey, but the bond market shows early signs of relief. Freddie Mac’s average 30-year fixed rate rose from 7.28% to 7.40%, while the 10-year Treasury yield later moved back below 5.29%. Wednesday’s inflation report is the next major test because a hotter reading could erase the improvement.
Want to understand why the market is moving this way? Here’s a closer look.
Why did mortgage rates move higher?
Freddie Mac’s October 8 survey showed the average 30-year fixed mortgage rate rose from 7.28% to 7.40%. That is a national weekly average, not a personal rate quote.
The bond market faced several pressures early last week. Concerns about European government debt pushed global yields higher. Oil and inflation worries also made investors cautious, while the Fed’s meeting notes showed that officials still see inflation as too high.
Mortgage bonds and mortgage rates usually move in opposite directions. When bond prices fall, mortgage rates can move higher. When bond prices rise, rate conditions may improve.
Why is the bond market improving now?
Higher yields began attracting buyers late last week. Strong demand at a 30-year Treasury auction also helped, and the 10-year Treasury yield closed meaningfully below 5.29% on October 8.
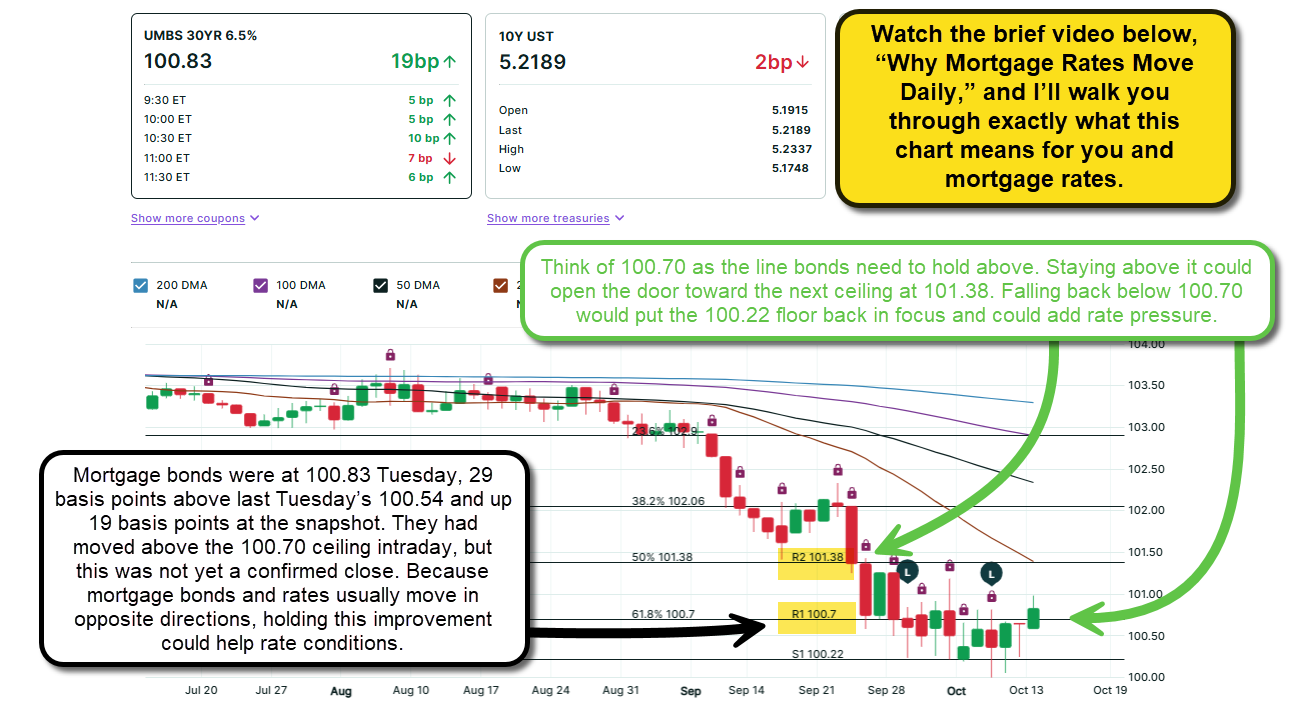
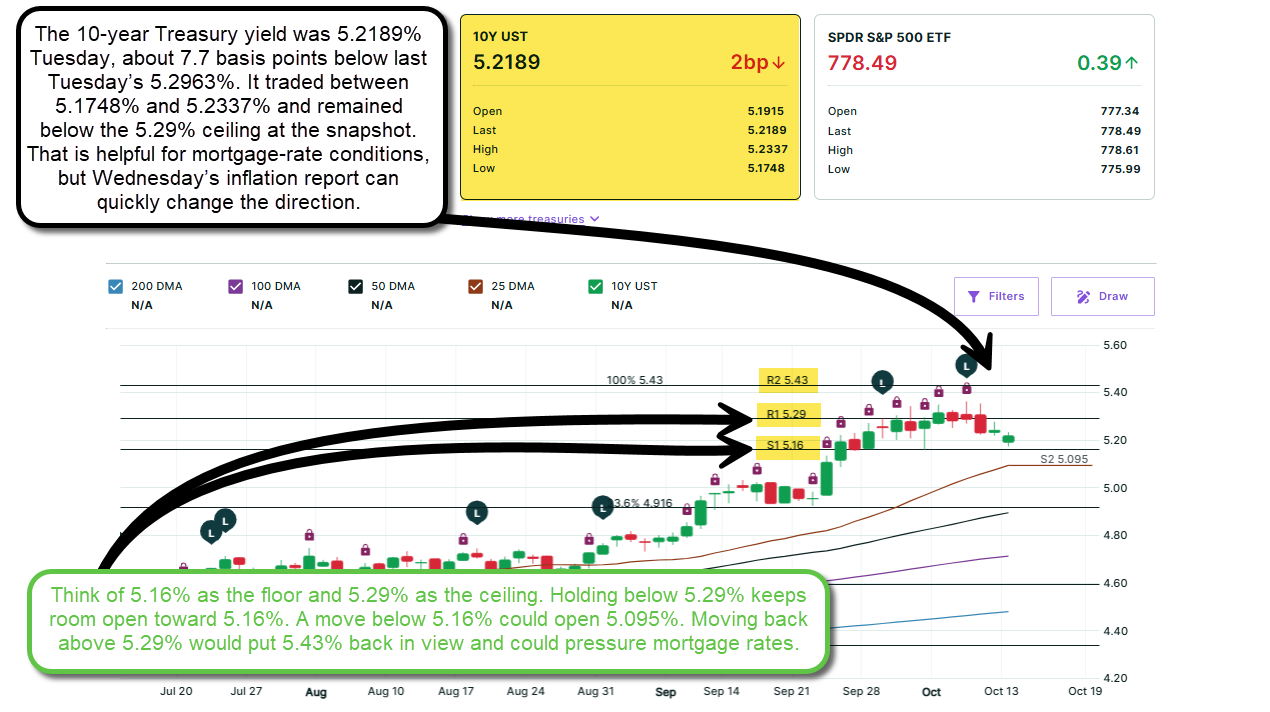
The improvement continued Tuesday. Mortgage bonds rose to 100.83 at the chart snapshot, and the 10-year yield was 5.2189%. These moves are helpful, but still early. Inflation data could quickly change the direction.
What do the bond charts tell us?
Mortgage bonds were 29 basis points higher than last Tuesday’s 100.54 reading. At Tuesday’s snapshot, they were also above the 100.70 ceiling. Because this was an intraday reading, it is not yet a confirmed close above that line.
The 10-year Treasury yield was about 7.7 basis points lower than last Tuesday’s 5.2963% reading. It remained below the 5.29% ceiling and above the 5.16% floor at the snapshot.
- If mortgage bonds hold above 100.70, the next ceiling is 101.38.
- If mortgage bonds fall back below 100.70, the 100.22 floor comes back into focus.
- If the 10-year yield stays below 5.29%, it has room to move toward the 5.16% floor. A move below 5.16% could open 5.095%.
- If the 10-year yield moves back above 5.29%, the next ceiling is 5.43%, which could add pressure to mortgage rates.
Think of support as a floor where a move may stop, and resistance as a ceiling the market must clear before it can improve further. These are levels to watch, not guarantees.
What could move rates this week?
Wednesday brings the Consumer Price Index, the week’s most important report for rates. It measures inflation paid by consumers. The Fed will also release its Beige Book, a collection of business reports from around the country.
Thursday brings the Producer Price Index, retail sales, and jobless claims. Friday brings import prices, industrial production, and capacity utilization. Hotter inflation or stronger spending could push yields higher. Cooler readings could help bonds and mortgage-rate conditions.
What does this mean for you?
Buyers should compare the full payment, cash needed, and loan structure instead of watching one advertised rate. Sellers may need to price carefully or offer a credit when buyers are sensitive about payments. Homeowners should compare the complete cost before deciding whether a refinance helps. Real estate professionals should prepare clients for quick market changes around Wednesday’s inflation report.
Bottom line
The latest national survey showed mortgage rates moving higher to 7.40%, but the bond charts have improved since that survey window. Mortgage bonds moving above 100.70 intraday and the 10-year yield staying below 5.29% are helpful. The next step is confirmation, and this week’s inflation data will be a major test.
If you are wondering what these market changes mean for your plans, call or message me. I will explain what matters without all the confusing market talk.
This is a general market update, not a personal rate quote. Freddie Mac’s 7.40% figure is the national weekly average for a 30-year fixed-rate mortgage as of October 8, 2026, up from 7.28% the prior week. Actual rates, costs, and eligibility depend on the borrower, property, loan program, points or credits, lock period, market conditions, and timing.
Mortgage Bond Market: Updated on 10-13-26
Mortgage Bond Market: Updated on 10-13-26
10 Year U.S. Treasury Bonds: Updated on 10-13-26
10 Year U.S. Treasury Bonds: Updated on 10-13-26
Watch the Trend, Not the Headline Rate
Below you’ll find the National Average Mortgage Rates as published for industry reference. These rates are for illustration only and reflect recently closed loans, not current market rates. Use this only for a general trend indicator. Your actual rate will depend on your financial profile and local market conditions, which is why getting pre-approved before you start shopping is key.
National Rate Averages
Historical Trend
Source: Optimal Blue Mortgage Market Indices (OBMMI). Indices reflect aggregate rate lock data. Learn more.
See What’s Happening: Locally & Nationally
The market moves fast. These two updates give you the clarity to stay ahead, so you can make confident, well-timed decisions, whether you’re buying, selling, or waiting.
MISSED A PREVIOUS WEEK'S UPDATE? CATCH UP HERE:
+ −Weekly Mortgage Market and Rate Update on 10-6-26
Weekly Mortgage Market and Rate Update on 9-28-26
Weekly Mortgage Market and Rate Update on 9-21-26
Weekly Mortgage Market and Rate Update on 9-14-26
Weekly Mortgage Market and Rate Update on 9-8-26
Weekly Mortgage Market and Rate Update on 8-31-26
Weekly Mortgage Market and Rate Update on 8-24-26
Weekly Mortgage Market and Rate Update on 8-17-26
Weekly Mortgage Market and Rate Update on 8-10-26
Weekly Mortgage Market and Rate Update on 8-3-26
Weekly Mortgage Market and Rate Update on 7-28-26
Weekly Mortgage Market and Rate Update on 7-22-26
Weekly Mortgage Market and Rate Update on 7-15-26
Weekly Mortgage Market and Rate Update on 7-7-26
Weekly Mortgage Market and Rate Update on 6-30-26
Weekly Mortgage Market and Rate Update on 6-23-26
Weekly Mortgage Market and Rate Update on 6-16-26
Weekly Mortgage Market and Rate Update on 6-9-26
Weekly Mortgage Market and Rate Update on 6-2-26
Weekly Mortgage Market and Rate Update on 5-26-26
Weekly Mortgage Market and Rate Update on 5-19-26
Weekly Mortgage Market and Rate Update on 5-12-26
Weekly Mortgage Market and Rate Update on 5-6-26
Weekly Mortgage Market and Rate Update on 4-27-26
Weekly Mortgage Market and Rate Update on 4-22-26
WE'RE HERE TO HELP
If you have any questions or need more information about our affordable home financing solutions, please don’t hesitate to CONTACT ME. My team and I are here to help you every step of the way!
Ready to start your home journey? Click here to submit your loan application today!
Best regards,
Michael Thayer, CMPS, CMA
NMLS #173264
Planet Home Lending, NMLS #17022
Explore Buyer & Seller Resources & Next Steps
+ −Market Timing vs. Market Strategy: When Is the Right Time to Buy... And More Importantly, Why?
Calculators & Loan Programs Questions Answered: Mortgage Programs & Financing Calculator
Smart Financing Strategies to Lower Your Monthly Mortgage Payment: Smart Mortgage Strategies & Financing Hacks
Homebuying Roadmap: Your Mortgage GPS
Moving To Middle Tennessee: Moving To Middle Tennessee Resource Center
Search Open Houses: View All Middle Tennessee Open Houses
Main Resource Hub: Buyers, Sellers, Realtors, and Builders Resources and Strategies
Video Transcripts
+ −Mortgage rates change every day, but most people don’t understand why… Or what it actually means for them. This page (updated weekly) is designed to simplify everything. In this video, you’ll learn:
- How to track mortgage rate trends
- What’s happening in the bond market
- The simple “teeter-totter” relationship between mortgage bonds and rates
- What’s driving rate movement (inflation, economic data, market reactions)
Whether you're:
- A homebuyer (first-time or moving up)
- A Realtor or builder advising clients
- A real estate investor
This resource helps you stay ahead of the market and make more confident decisions. You’ll also find:
- Local Nashville market data
- National housing trends
- Weekly outlooks on where rates may be heading next
Bookmark this page and check back weekly to stay informed.
- Go to: www.michaelthayer.com
- Scroll down to "Weekly Mortgage Market and Rate Update"
- Save the link to check back for the weekly updates.
Have questions or want a breakdown for your local market? Reach out; I am happy to help.
Why Rates Move Daily:
Alright, before we get into this, let me be very clear: if anyone is telling you mortgage rates move for some random reason or pointing to anything other than what I’m about to explain, they’re wrong; you’re talking to the wrong person. Mortgage rates are driven by two core factors: inflation and the economic data that impacts it, and more specifically, how those factors influence the way mortgage bonds trade on Wall Street. That’s what ultimately drives the rates you and I see every day, and it really is that simple. Some people point to the 10-year Treasury as an indicator, and while it can be helpful, it doesn’t always tell the full story and can be misleading at times. Most people can’t explain this clearly, and that’s why this exists: to break it down simply so you finally have clarity. It can feel confusing because it’s counterintuitive, but once you understand that it works in the opposite way you might expect, it becomes much easier. Think of it like a teeter-totter: when one side goes up, the other side comes down, and that’s exactly how mortgage bonds and mortgage rates behave. What you’re looking at in a bond chart is daily movements shown as candlesticks; each bar represents one full day of trading. Green is good, meaning bonds improved and rates typically move lower; red is bad, meaning bonds declined and rates move higher. Now tie that back to the teeter-totter. When bond yields improve, rates get better; when bond yields decline, rates get worse. The biggest factor influencing all of this is inflation, because inflation erodes the value of bonds over time. When inflation rises or is expected to rise, bonds struggle, and when bonds struggle, mortgage rates increase. When inflation cools, bonds improve, and rates can move lower. So if you’re watching one thing, watch inflation; it’s the key driver. If inflation comes in higher than expected, expect rates to rise; if it cools, rates can improve. The good news is you don’t have to figure this out on your own. I break this down and update it every week, so you can understand the trend, see what’s happening, and make better decisions. Most people fear what they don’t understand, and that costs them money, but when you have clarity, you make stronger, more confident decisions. Use this as your resource, come back to it, and if you have questions, reach out. I’m here to help make sense of it all.
Additional Information & Reference Guides
+ −Mortgage Bond Market: Updated on 8-17-26 Image Overview
+ −What this image communicates
A reader encountering “Mortgage Bond Market: Updated on 8-17-26” should immediately recognize the dated mortgage-market evidence question inside “Weekly Mortgage Market and Rate Update.” The visual's role is primary visual message, so it must make one topic recognizable at a glance and give the reader a clear entry point into the deeper explanation on the page rather than merely repeat the headline. The image makes “Mortgage Bond Market: Updated on 8-17-26” the dominant visual message and gives the reader a defined entry point into the page's argument. The wording identifies what deserves attention first; the surrounding design establishes whether the reader is looking at a claim, a choice, a sequence, or a practical resource. That distinction determines what evidence should be gathered before the message is applied.
Why it belongs on this page
The August 17 market update reports relief after cooler inflation and weaker retail sales, followed by renewed pressure as oil climbed near $83 amid conflict and shipping disruption. The bond chart highlights support near 101.39, a smaller hurdle near 101.43, and a more important ceiling near 101.72. Those levels describe the chart at that update; they are not borrower pricing or permanent floors and ceilings. The primary visual message role of “Mortgage Bond Market: Updated on 8-17-26” is the reason this image belongs at this point in “Weekly Mortgage Market and Rate Update.”
How a reader can use it
Use “Mortgage Bond Market: Updated on 8-17-26” for its stated primary visual message job on “Weekly Mortgage Market and Rate Update.” Identify the claim, chart, comparison, process, property feature, or strategy shown and connect it to the exact decision the page addresses. The working notes for this panel should record the literal claim or comparison shown, the page fact it supports, the source behind that fact, and the decision the reader should make next. That record lets the reader separate a market explanation from the rate and costs available to one borrower for one property without asking this image to answer a different stage of the decision.
What still must be verified
Keep the visual in its proper role. A dated market image cannot guarantee a future rate, reproduce a Loan Estimate, or show the pricing adjustments attached to a particular credit, occupancy, property, loan amount, or lock period. If a later disclosure, source update, appraisal, inspection, title item, program rule, or contract term conflicts with “Mortgage Bond Market: Updated on 8-17-26,” the current controlling evidence takes priority. On “Weekly Mortgage Market and Rate Update,” that safeguard applies specifically to the primary visual message role assigned to “Mortgage Bond Market: Updated on 8-17-26.”