Why Today’s Buyers Still Have Opportunity
Higher Rates Have Created Hesitation
But that hesitation may also be creating an opportunity for today’s buyers.
Today’s housing market feels very different from the ultra-competitive frenzy of 2020 and 2021.
Higher mortgage rates have caused many buyers to pause:
➡️ Waiting For Lower Rates
➡️ Waiting For Better Affordability
➡️ Waiting For More Certainty
➡️ Waiting For “The Right Time”
But that hesitation has also created something many buyers overlook:
More negotiating leverage.
And in many markets today, buyers may still have opportunities that become much harder to find once competition returns more aggressively.
Today's Opportunity Isn't Just The Rate It's The Leverage
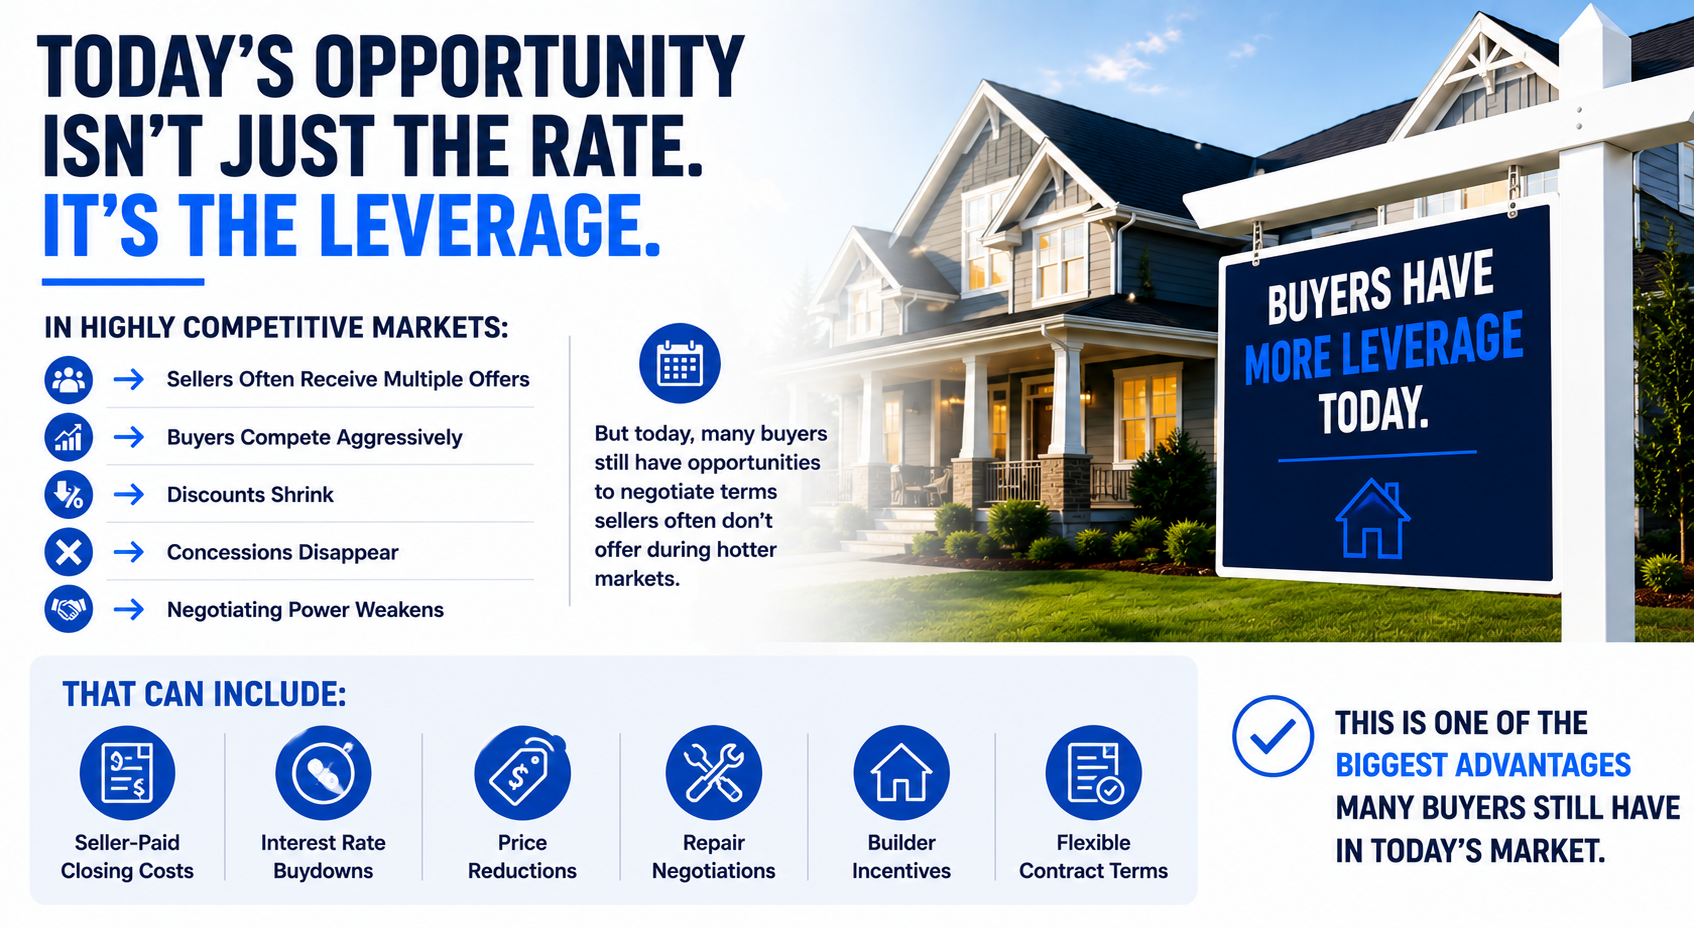
Today's Opportunity Isn't Just The Rate It's The Leverage
Buyers Are Still Negotiating Meaningful Discounts
One of the biggest misconceptions in today’s market is that buyers no longer have negotiating power.
But in many areas of the country:
buyers are still negotiating:
➡️ Price Reductions
➡️ Seller Credits
➡️ Closing Cost Assistance
➡️ Interest Rate Buydowns
➡️ Repair Negotiations
➡️ Builder Incentives
And while those opportunities still exist today…
The data also show they may be slowly becoming less common as affordability improves and buyer activity starts to return.
Buyers Are Scoring Discounts But Literally Less Frequently
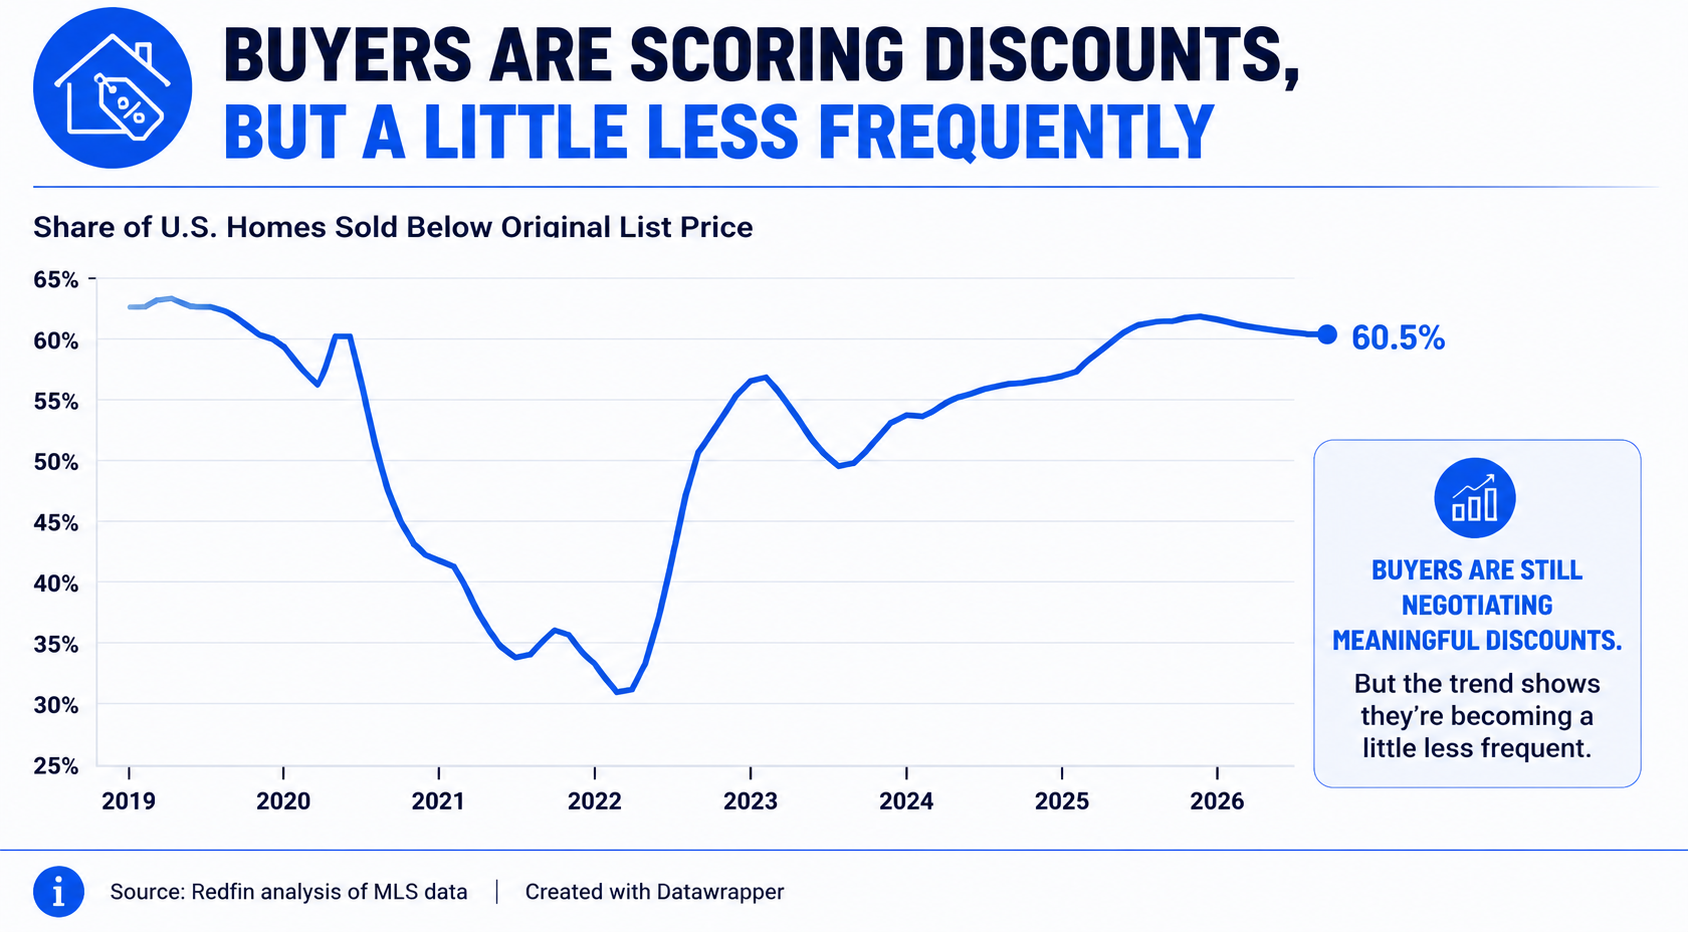
Buyers Are Scoring Discounts But Literally Less Frequently
The Interest Rate May Be Temporary. But The Price You Pay For The Home Becomes Permanent.
Many buyers focus almost entirely on the mortgage rate.
Experienced buyers often focus just as heavily on:
➡️ The Total Acquisition Cost
➡️ Negotiating Leverage
➡️ Seller Concessions
➡️ Cash Preserved At Closing
➡️ And Long-Term Financial Positioning
Because while mortgage rates may change over time…
The price you pay for the property becomes permanent.
That’s one of the biggest reasons many buyers today are focused on:
Securing the strongest overall deal structure possible.
The Lowest Rate Doesn’t Always Create The Lowest Total Cost To Buy
The Lowest Rate Doesn’t Always Create The Lowest Total Cost To Buy
Mortgage Rates Can Change. Acquisition Cost Is Permanent.
This is one of the most important concepts buyers often overlook.
While future mortgage rates are impossible to predict…
Historically, many buyers have refinanced when market conditions improved.
That’s why many buyers today are focused on:
➡️ Locking In The Home
➡️ Negotiating The Strongest Possible Terms
➡️ Preserving Cash Today
➡️ Improving The Payment Later If Rates Decline
In many scenarios, refinancing later may significantly improve affordability.
And depending on the loan structure, many buyers may be able to refinance strategically while minimizing out-of-pocket costs.
Mortgage Rates Can Change But The Price You Pay For The House Is Permanent
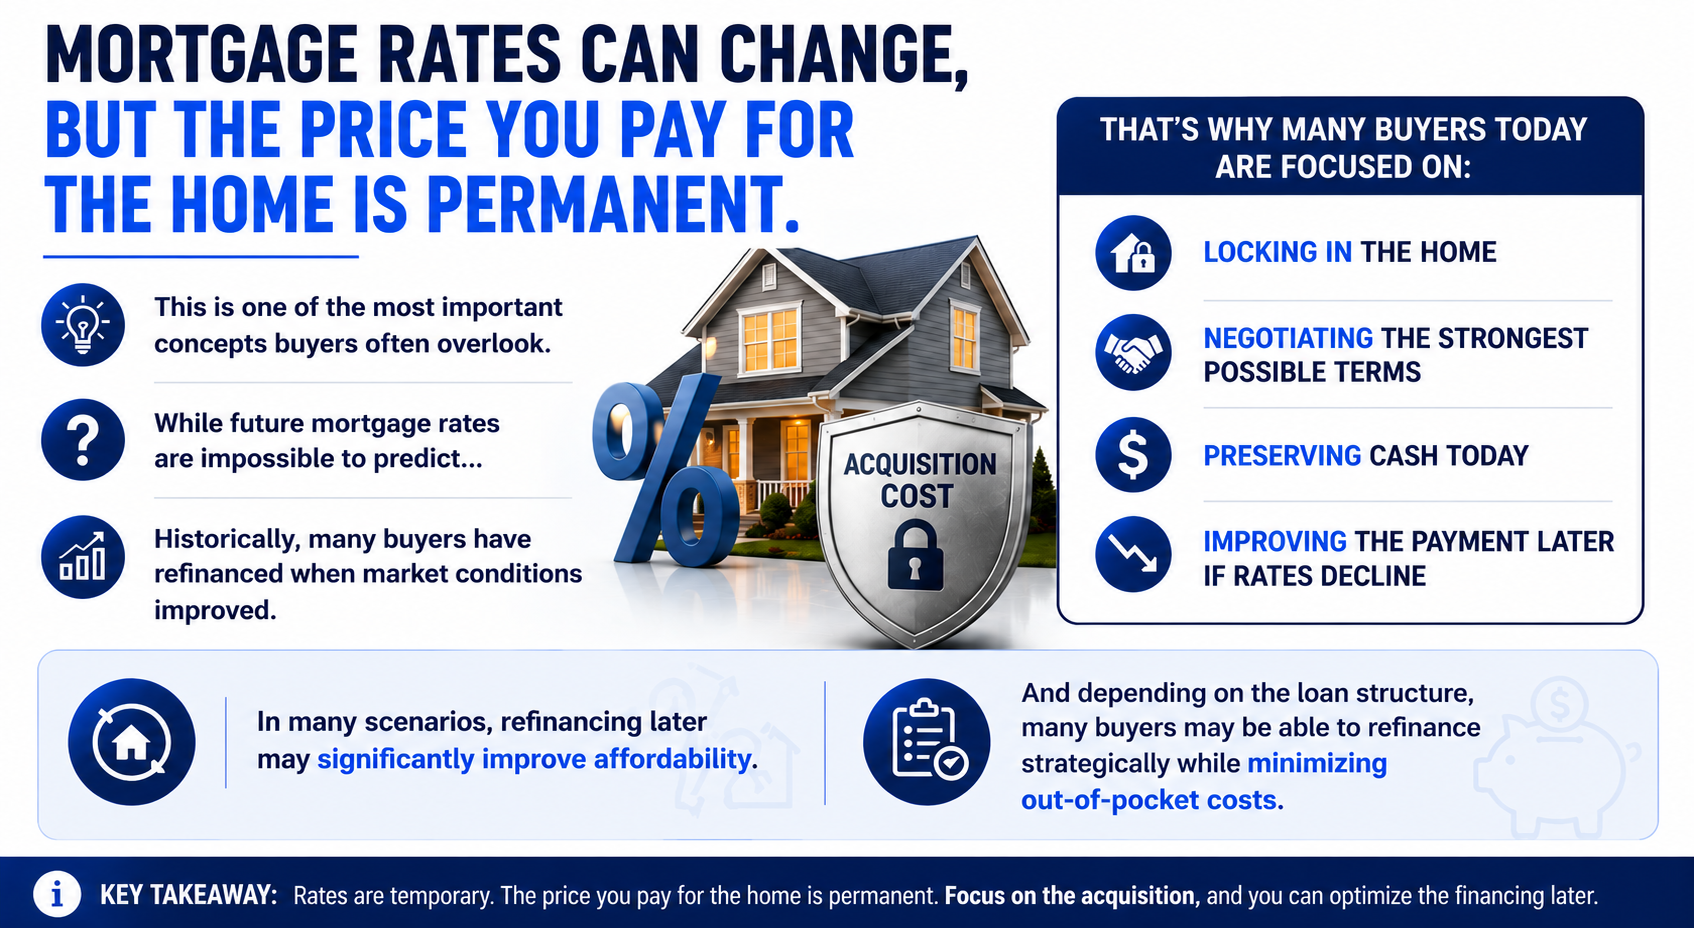
Mortgage Rates Can Change But The Price You Pay For The House Is Permanent
What Happens When Rates Drop?
This is where many buyers miss the bigger picture.
As we covered on the previous page:
Lower rates can improve affordability.
But they can also bring millions of buyers back into the market simultaneously.
And when competition returns:
➡️ Multiple Offers Often Increase
➡️ Sellers Gain More Leverage
➡️ Discounts Become Less Common
➡️ Concessions Shrink
➡️ Inventory Moves Faster
➡️ Home Prices Can Face Renewed Upward Pressure
That’s one of the biggest reasons today’s buyers may still have a meaningful opportunity before competition intensifies further.
But this is where many buyers underestimate how quickly housing markets can change once affordability improves.
Waiting For Lower Rates May Also Mean
➡️ More Competition
➡️ Higher Prices
➡️ Fewer Concessions
➡️ Less Negotiating Leverage
➡️ Faster-Moving Inventory
That’s why the “best” time to buy is often more complicated than simply waiting for the lowest possible interest rate.
Waiting For Lower Rates May Also Mean — Documentation Calculations and Planning Details
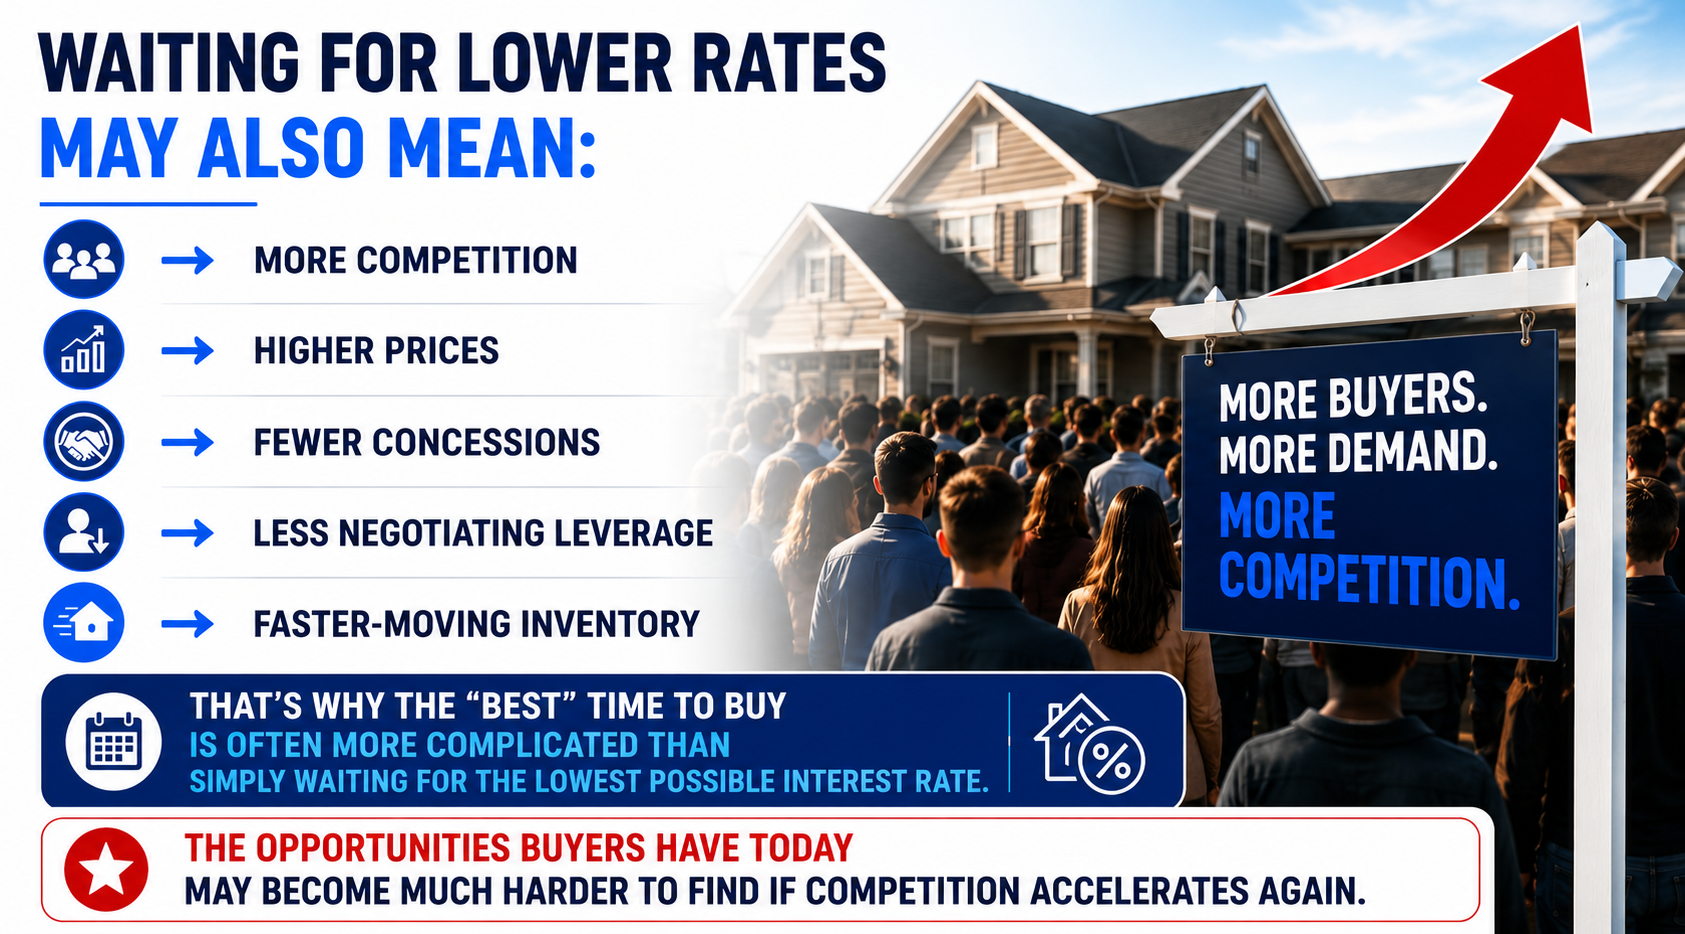
Waiting For Lower Rates May Also Mean — Documentation Calculations and Planning Details
This Is Where Many Buyers Underestimate How Quickly Housing Markets Can Change Once Affordability Improves
Lower rates may improve payments, but they can also increase competition.
This page isn’t saying today is perfect. It’s explaining why opportunity may still exist.
Every buyer’s situation is different.
But many buyers today may still have opportunities that become much harder to find once competition returns more aggressively.
That’s why understanding:
➡️ Leverage
➡️ Concessions
➡️ Pricing
➡️ Affordability
➡️ Competition
➡️ Long-Term Strategy
matters so much in today’s market.
Every Buyer’s Situation Is Different
The housing market is complex.
And unfortunately, many buyers today are hearing conflicting opinions, emotional headlines, social media hot takes, and one-size-fits-all advice without ever being shown the full picture.
That’s why this presentation series was created: to help buyers better understand the bigger picture of housing affordability, competition, leverage, market psychology, mortgage rates, and long-term financial strategy, and how these factors often work together rather than focusing on only one piece of the puzzle.
Click the links below to continue exploring the Housing Market Series:
➡️ The Supply Problem Most People Don’t Realize Exists
➡️ Why Do Home Prices Keep Rising?
➡️ What History Shows Us About Home Values
➡️ What Happens When Rates Drop?
➡️ Why Waiting Could Create More Competition
➡️ Today’s Buyers Have More Leverage Than They Think
If you’d like help understanding how these market dynamics may impact your specific situation, we’re happy to walk through the numbers with you and help you evaluate your options clearly and strategically.
➡️ Schedule Your Strategy Call Here
Best regards,
Michael Thayer, CMPS, CMA
NMLS #173264
Planet Home Lending, NMLS #17022
Explore Buyer & Seller Resources & Next Steps
+ −Market Timing vs. Market Strategy: When Is the Right Time to Buy... And More Importantly, Why?
Calculators & Loan Programs Questions Answered: Mortgage Programs & Financing Calculator
Smart Financing Strategies to Lower Your Monthly Mortgage Payment: Smart Mortgage Strategies & Financing Hacks
Homebuying Roadmap: Your Mortgage GPS
Moving To Middle Tennessee: Moving To Middle Tennessee Resource Center
Search Open Houses: View All Middle Tennessee Open Houses
Main Resource Hub: Buyers, Sellers, Realtors, and Builders Resources and Strategies
Additional Information & Reference Guides
+ −Welcome Video Transcript
+ −Video Transcript
00:00
One of the biggest mistakes I see buyers make in today's market is assuming that the lowest interest rate automatically creates the best financial outcome. And honestly, that's not always true.
00:10
Many times, the lowest rate combined with the wrong financial strategy can cost you thousands. I'm Michael Thayer, I'm a mortgage advisor based in Nashville, Tennessee, serving clients nationwide.
00:22
Most people think about buying a home. They focus almost entirely.
00:27
On one thing the interest rate.
00:30
But experienced buyers often look at something much bigger. Total acquisition costs, seller concessions, negotiating leverage, cash preserved at closing, long-term financial strategy.
00:43
And that matters because today's market is very different than the ultra-competitive frenzy we saw a few years ago.
00:50
And in many markets right now, buyers still have the opportunity to negotiate price reductions, seller paid closing costs, interest rate buy-downs, repair credits, builder incentives, but…
01:02
Here's the part many buyers miss.
01:06
When mortgage rates eventually decline meaningfully, Millions of buyers.
01:10
Millions of buyers who have been sitting and waiting on the sidelines may come back into the market at the same time.
01:16
And when competition increases, Discounts off to shrink or disappear entirely. Seller concessions? Gone. Inventory moves faster.
01:25
Multiple offer situations return. And home prices can face renewed upward pressure. And that's why strategic buyers today aren't just asking, what's the lowest rate? They're asking, what's the smartest overall financial structure?
01:40
Because you can change your interest rate later, when rates drop.
01:46
But, the price you pay for the home?
01:49
That becomes permanent.
01:52
That's the entire concept behind the catchphrase. Marry the house, Date the right.
01:58
This presentation breaks down why total cost matters, how leverage impacts affordability, what happens when competition returns, and why.
02:07
Some buyers today may still have opportunities to become… that are going to become much harder to find in the near future, when rates drop and competition returns. So, click below, compare the numbers for yourself, they can be eye-opening. We'll talk to you soon.
Today's Opportunity Isn't Just The Rate It's The Leverage Image Overview
+ −What this image communicates
The purpose of “Today's Opportunity Isn't Just The Rate It's The Leverage” is to organize one part of “Why Today’s Buyers Still Have Opportunity” around a primary visual message. It helps the reader understand how to make one topic recognizable at a glance and give the reader a clear entry point into the deeper explanation on the page and keeps the discussion centered on what the chart or comparison says about supply, demand, prices, rates, equity, leverage, or competition at the geography and period actually measured. The image makes “Today's Opportunity Isn't Just The Rate It's The Leverage” the dominant visual message and gives the reader a defined entry point into the page's argument. The wording identifies what deserves attention first; the surrounding design establishes whether the reader is looking at a claim, a choice, a sequence, or a practical resource. That distinction determines what evidence should be gathered before the message is applied.
Why it belongs on this page
The buyer-opportunity page argues that rate is only one part of the transaction. The primary visual message role of “Today's Opportunity Isn't Just The Rate It's The Leverage” is the reason this image belongs at this point in “Why Today’s Buyers Still Have Opportunity.”
How a reader can use it
Use “Today's Opportunity Isn't Just The Rate It's The Leverage” for its stated primary visual message job on “Why Today’s Buyers Still Have Opportunity.” Identify the claim, chart, comparison, process, property feature, or strategy shown and connect it to the exact decision the page addresses. The working notes for this panel should record the literal claim or comparison shown, the page fact it supports, the source behind that fact, and the decision the reader should make next. That record lets the reader use market context to improve timing and negotiation questions without converting a broad statistic into a property-level prediction without asking this image to answer a different stage of the decision.
What still must be verified
The image is valuable because it frames the right issue, not because it proves the answer. National or regional data cannot establish a specific home's value, condition, future appreciation, market time, offer activity, or the result of waiting. “Today's Opportunity Isn't Just The Rate It's The Leverage” remains educational until the current borrower, property, market, and transaction evidence supports a specific conclusion. On “Why Today’s Buyers Still Have Opportunity,” that safeguard applies specifically to the primary visual message role assigned to “Today's Opportunity Isn't Just The Rate It's The Leverage.”
Buyers Are Scoring Discounts But Literally Less Frequently Image Overview
+ −What this image communicates
The visible message in “Buyers Are Scoring Discounts But Literally Less Frequently” directs attention to homebuying decision framework on “Why Today’s Buyers Still Have Opportunity.” The image functions as a primary visual message: it should make one topic recognizable at a glance and give the reader a clear entry point into the deeper explanation on the page. That gives the reader a specific reason to slow down before acting. The visual centers “Buyers Are Scoring Discounts But Literally Less Frequently” on a specific housing or listing decision. It connects the visible promise to the property, the people involved, and the transaction sequence instead of leaving the message as abstract marketing. A useful reading separates what can be illustrated now from what still depends on the home's condition, the negotiated terms, verified financing, and current market response.
Why it belongs on this page
Its four images focus on leverage, the changing frequency of discounts, the permanence of the purchase price relative to a changeable financing structure, and what can accompany lower rates. The primary visual message role of “Buyers Are Scoring Discounts But Literally Less Frequently” is the reason this image belongs at this point in “Why Today’s Buyers Still Have Opportunity.”
How a reader can use it
Use “Buyers Are Scoring Discounts But Literally Less Frequently” for its stated primary visual message job on “Why Today’s Buyers Still Have Opportunity.” Identify the claim, chart, comparison, process, property feature, or strategy shown and connect it to the exact decision the page addresses. The working notes for this panel should record the literal claim or comparison shown, the page fact it supports, the source behind that fact, and the decision the reader should make next. That record lets the reader turn a broad housing question into a smaller set of facts, tradeoffs, and next actions without asking this image to answer a different stage of the decision.
What still must be verified
The final safeguard is verification. The image provides education, not a loan decision, property valuation, legal conclusion, tax result, inspection finding, insurance commitment, or guarantee of future market performance. A reader should leave “Buyers Are Scoring Discounts But Literally Less Frequently” knowing what to ask and what to gather—not believing that a graphic has already supplied an approval, valuation, legal conclusion, or guaranteed outcome. On “Why Today’s Buyers Still Have Opportunity,” that safeguard applies specifically to the primary visual message role assigned to “Buyers Are Scoring Discounts But Literally Less Frequently.”
Mortgage Rates Can Change But The Price You Pay For The House Is Permanent Image Overview
+ −What this image communicates
The “Mortgage Rates Can Change But The Price You Pay For The House Is Permanent” image turns the central issue on “Why Today’s Buyers Still Have Opportunity” into a visible primary visual message. It is there to make one topic recognizable at a glance and give the reader a clear entry point into the deeper explanation on the page, while the page supplies the evidence and explanation needed to evaluate how goals, payment comfort, cash needs, property fit, timing, risk, and professional responsibilities come together. The image makes “Mortgage Rates Can Change But The Price You Pay For The House Is Permanent” the dominant visual message and gives the reader a defined entry point into the page's argument. The wording identifies what deserves attention first; the surrounding design establishes whether the reader is looking at a claim, a choice, a sequence, or a practical resource. That distinction determines what evidence should be gathered before the message is applied.
Why it belongs on this page
Readers should compare concessions, competition, price, payment, refinancing costs, and future uncertainty rather than assuming a later rate automatically creates a better deal. The primary visual message role of “Mortgage Rates Can Change But The Price You Pay For The House Is Permanent” is the reason this image belongs at this point in “Why Today’s Buyers Still Have Opportunity.”
How a reader can use it
Use “Mortgage Rates Can Change But The Price You Pay For The House Is Permanent” for its stated primary visual message job on “Why Today’s Buyers Still Have Opportunity.” Identify the claim, chart, comparison, process, property feature, or strategy shown and connect it to the exact decision the page addresses. The working notes for this panel should record the literal claim or comparison shown, the page fact it supports, the source behind that fact, and the decision the reader should make next. That record lets the reader turn a broad housing question into a smaller set of facts, tradeoffs, and next actions without asking this image to answer a different stage of the decision.
What still must be verified
The final safeguard is verification. The image provides education, not a loan decision, property valuation, legal conclusion, tax result, inspection finding, insurance commitment, or guarantee of future market performance. A reader should leave “Mortgage Rates Can Change But The Price You Pay For The House Is Permanent” knowing what to ask and what to gather—not believing that a graphic has already supplied an approval, valuation, legal conclusion, or guaranteed outcome. On “Why Today’s Buyers Still Have Opportunity,” that safeguard applies specifically to the primary visual message role assigned to “Mortgage Rates Can Change But The Price You Pay For The House Is Permanent.”
Waiting For Lower Rates May Also Mean — Documentation Calculations and Planning Details Image Overview
+ −What this image communicates
The “Waiting For Lower Rates May Also Mean — Documentation Calculations and Planning Details” image turns the central issue on “Why Today’s Buyers Still Have Opportunity” into a visible evidence and calculation layer. It is there to separate measurable inputs from assumptions and reveal which figures or documents control the comparison, while the page supplies the evidence and explanation needed to evaluate how goals, payment comfort, cash needs, property fit, timing, risk, and professional responsibilities come together. The image organizes “Waiting For Lower Rates May Also Mean” as a working checklist rather than a promise that every file will require the same items. It groups the records or questions a reader should anticipate, shows where an exception may add work, and provides a way to notice missing information before a deadline. The visible list is a preparation tool; the final request still comes from the responsible reviewer or program.
Why it belongs on this page
The buyer-opportunity page argues that rate is only one part of the transaction. The evidence and calculation layer role of “Waiting For Lower Rates May Also Mean” is the reason this image belongs at this point in “Why Today’s Buyers Still Have Opportunity.”
How a reader can use it
Use “Waiting For Lower Rates May Also Mean” for its stated evidence and calculation layer job on “Why Today’s Buyers Still Have Opportunity.” Write down every input, source, date, unit, estimate, and unresolved condition before relying on a calculation or side-by-side result. The working notes for this panel should record each number, unit, source, date, estimate, document, calculation method, and unresolved input that could change the comparison. That record lets the reader turn a broad housing question into a smaller set of facts, tradeoffs, and next actions without asking this image to answer a different stage of the decision.
What still must be verified
The graphic has a defined limit: The image provides education, not a loan decision, property valuation, legal conclusion, tax result, inspection finding, insurance commitment, or guarantee of future market performance. Use “Waiting For Lower Rates May Also Mean — Documentation Calculations and Planning Details” to understand and organize the issue, then rely on current source material for any number, eligibility rule, property fact, deadline, or professional conclusion. On “Why Today’s Buyers Still Have Opportunity,” that safeguard applies specifically to the evidence and calculation layer role assigned to “Waiting For Lower Rates May Also Mean.”